Posts

An isolated gas station on an empty desert road at night, its canopy lit and the price sign dark, with an amber glow on the horizon

Wednesday’s CPI: the headline will look scary, but the real risk is somewhere else

Hi trader,

the last time I wrote to you about a CPI, on 11 September, the market had the Fed hike at 70%.

And I told you that 70% was the worst place to be caught by a data release.

Five days later the Fed really did hike, the first hike in more than three years, rates at 3.75-4.00%.

This afternoon the September CPI comes out, and the picture has flipped.

The market now puts the end-of-month hike at around 20%.

And I’ll tell you right away why that worries me more, not less.

What comes out today, and when

The US September CPI, the consumer price index.

The Bureau of Labor Statistics publishes it on Wednesday 14 October at 8:30 am New York time, which is 13:30 in London and here in the Canary Islands, and 14:30 in Italy.

Here is what the market expects, compared with August:

What Expected September August
Headline CPI, year on year 3.6-3.7% 3.4%
Headline CPI, month on month +0.6% +0.4%
Core CPI (ex food and energy), year on year 2.4-2.5% 2.4%
Core CPI, month on month +0.2% +0.3%

On the core, the forecasts are bunched almost entirely around +0.2%.

Keep that in mind, because that is where the risk is hiding.

Oh, and tomorrow, Thursday, producer prices come out too.

So this afternoon does not close the story, it opens a two-day stretch.

Today’s headline will look scary

I’m telling you in advance, so you don’t get a fright at 8:30.

A +0.6% on the month would be the strongest monthly rise since April.

The reason is always the same: gasoline.

In August gasoline in the CPI was already up 27.4% on the year, and energy as a whole 16.3%.

In September gasoline rose again, and at the end of the month diesel hit its all-time record, just above 6.5 dollars a gallon as a national average.

Brent is trading around 105 dollars these days.

On Sunday Trump announced an “energy truce” between Russia and Ukraine, no more attacks on energy facilities.

Moscow did not confirm it, the attacks carried on, and on Monday oil closed higher instead of lower.

And the Middle East, which is what pushed the barrel all the way up there, has not calmed down at all.

In plain words: today’s headline is written by the barrel, and these days the barrel is written by the news from the front lines.

And that is exactly why the headline, for anyone who trades, matters less than it looks.

At the Fed almost everyone knows it’s gasoline.

The market knows it’s gasoline.

The phone notifications will talk about “inflation at a multi-month high”, and they will be right, but that is not the number the end-of-month game is played on.

August’s core was dirty

And here comes the part almost nobody tells you.

In August the core came out at +0.3%, above the +0.2% expected.

The market noticed right away: short-term yields went up, because a core above expectations is exactly what the Fed does not want to see.

But if you open the report and look inside, a slice of that +0.3% was not inflation spreading.

It was two odd items.

Phone services, up 5.4% in a single month because of price hikes and plan changes at AT&T and T-Mobile, added about a tenth of a point to the core on their own.

And hotels, +2.4% after two months of similar declines, which is a rebound more than a trend.

Take those two things out and August goes back to being a normal month.

That is why almost everyone expects a September core at +0.2%: not because inflation is cooling, but because those two items don’t repeat.

It’s like a puncture in qualifying.

The lap time is bad, but it tells you nothing about race pace.

So what do I look at inside today’s core?

One item, before all the others: airline fares.

Because a plane ticket is a service, but there is fuel inside it.

In August flights were already up 23.4% on the year: the barrel has been passing from fuel into services for months, and the question is whether it speeds up.

That is still an indirect effect, fuel going into the price of a service.

The next step is the one the ECB had put into its projections in September, the second-round effect: wages and price lists adjusting.

That is where the price rise stops being gasoline and becomes something else.

Why this time the risk is all on one side

Back to that 20%.

How did we get there?

Up to 28 September the market had the end-of-month hike at around 70-75%.

Then in four days three things happened.

On 29 September John Williams, the president of the New York Fed, said there is no urgency and that another move could come towards the end of the year.

The October odds collapsed right there.

The next day August PCE, the index the Fed actually uses for its 2% target, came out a touch below expectations.

And on 2 October the September jobs report came out very weak, 29,000 jobs against an estimate of around 90,000, unemployment up from 4.1% to 4.2%.

Result: October almost priced out, and the whole bet moved to December, where a hike is priced at around 85%.

So the story the market has told itself is this: October on hold, December hike.

Now think about how a price built like that reacts.

If the core comes out at +0.2% today, the market says “I knew it”.

Movement, sure, but inside a script already written.

If it comes out at +0.3% or higher, above almost every forecast, that 20% for October is no longer a 20%.

And a bet that has to be repriced from 20 to 50 in one afternoon is far more violent than one going from 70 to 80.

In September the hike was in the price, and the data could only confirm it or disappoint.

Today the hike is almost priced out, and only one surprise really hurts.

There is also the opposite tail, and it’s not one to dismiss.

Core at +0.1% with a labour market creating 29,000 jobs, and someone at the table will start asking whether December is really needed.

The 85% for December would deflate, and that really would be a field day for equities.

Less likely, but possible.

My point is a different one: the market is leaning on a single story, and the dangerous afternoons are the ones when the story breaks.
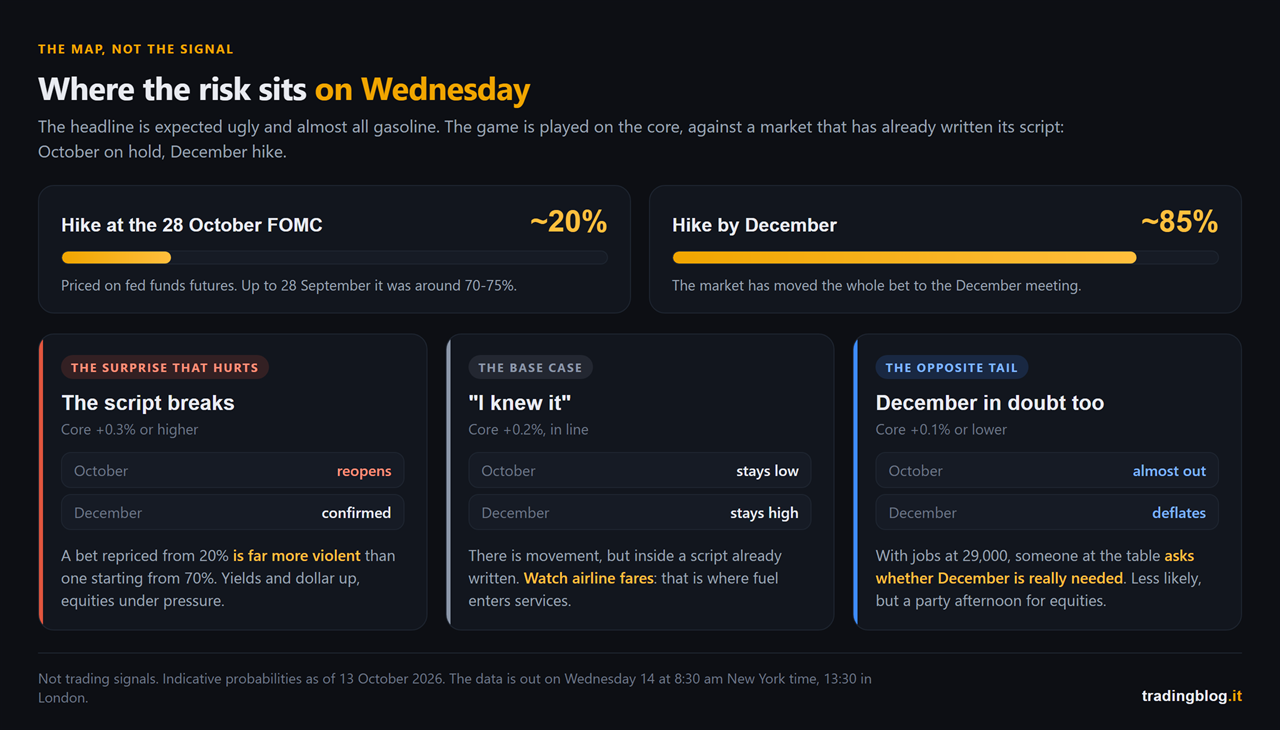
Diagram of where the risk sits on the September CPI: a Fed hike in October priced around 20% and in December around 85%, and what a core print of +0.3% or higher, +0.2%, or +0.1% or lower tends to move
Where the risk sits on Wednesday. With the October hike priced at around 20% and the December one at around 85%, here is what each core outcome tends to move. These are not signals, it is the map.

A Fed pulled two ways

There’s one last thing that makes this CPI different from September’s.

In September the Fed had one problem: inflation.

Now it has two, and they pull in opposite directions.

On one side prices rising because of energy, with the US 10-year above 5% and the president of the Cleveland Fed, Beth Hammack, saying rates need to be higher because inflation is broadening.

On the other a labour market that this year has created 68,000 jobs a month on average, and that in September created less than half of that.

The minutes of the September meeting say the committee sees another hike by the end of the year.

They don’t say when.

And when a central bank doesn’t say when, the data decides.

Today is the data.

How I handle it

The rules are the usual ones, because CPI days all look alike.

I don’t enter on the 8:30 spike.

First the market reads the headline, which today will be ugly and already expected.

Then it reads the core.

Then, if it’s someone who works properly, it opens the detail and looks at what’s inside.

The move that holds until the evening is almost always born at the second or third pass, not the first.

I show up with the map already drawn.

Calendar, levels, and where the options market has its walls on the S&P and the Nasdaq.

On a day like this part of the move is made by market makers hedging, not by the news, and that’s gamma exposure.

I check it on the Thunder Desk, which is free and puts the macro calendar and gamma on the same screen.

The point isn’t the tool, it’s opening it in the morning, not at 8:29 with the position already open.

I cut size before, not after.

If a position is still alive at 8:30, the spread can widen and the stop can get filled a few ticks further away.

What that scenario really costs me I work out now, with numbers, not by eye.

And I log the reaction, not the result.

What I expected, what came out, what price did in the first five minutes and what it did by 10 am.

Do it today, and do it again at the end of the month with the FOMC.

A few days like this in the diary and your recurring behaviour around macro data shows up on its own.

Three takeaways

  1. Today’s headline will be ugly, and it’s already written. Headline expected at +0.6% on the month and 3.6-3.7% on the year, almost all energy, meaning gasoline. That’s not where October is decided.
  2. August’s core was inflated by two items that don’t repeat. A +0.2% today doesn’t mean inflation is cooling, and inside it airline fares are worth watching, the point where the barrel enters services.
  3. The market has already decided: October on hold, December hike. With October at around 20%, the surprise that hurts most is a core at +0.3% or higher. You don’t need to guess it, you need to know beforehand what you do if it comes.

If you missed the previous episodes, the piece on the August CPI is where the headline versus core discussion started, and the piece on the September hike explains why from here on every inflation print weighs double.

The dangerous number is not the one the market fears. It’s the one the market has stopped fearing.

— tradingblog.itPosta su X

I’ll close with what I tell myself every time I see a calm market before a release.

Calm doesn’t mean safe.

It means everyone has bet on the same story.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.

A stone staircase climbing through the darkness towards an amber glow at the top, between rocks and dark structures, with no end in sight

It was not a move. It was the start of a cycle.

Hi trader,

on 16 September the Fed raised rates for the first time in more than three years.

In the six days that followed the Nasdaq printed two record highs in a row and the VIX fell 20%.

If your reaction is “the market did not get it”, stop for a second. Because the numbers say the opposite: the market got it perfectly well, and what it got is more interesting than the hike.

Ok, vamos.

What happened, in three lines

Twenty-five basis points, from 3.50-3.75% to 3.75-4.00%. Vote unanimous, twelve to zero, no dissent. First hike after more than three years of standing still or cutting.

You read all of that everywhere on 16 September, and a week later it is worth nothing.

What is worth something sits in the projections the committee publishes alongside the decision.

The real headline is not 2026. It is 2027.

Alongside the decision, the committee publishes its own rate projections. Eighteen dots on a chart, which become seventeen on the years further out, because one participant did not submit projections for 2028 and 2029.

2026 is the part that ended up in the headlines: at least one more hike by year end, say sixteen dots out of eighteen.

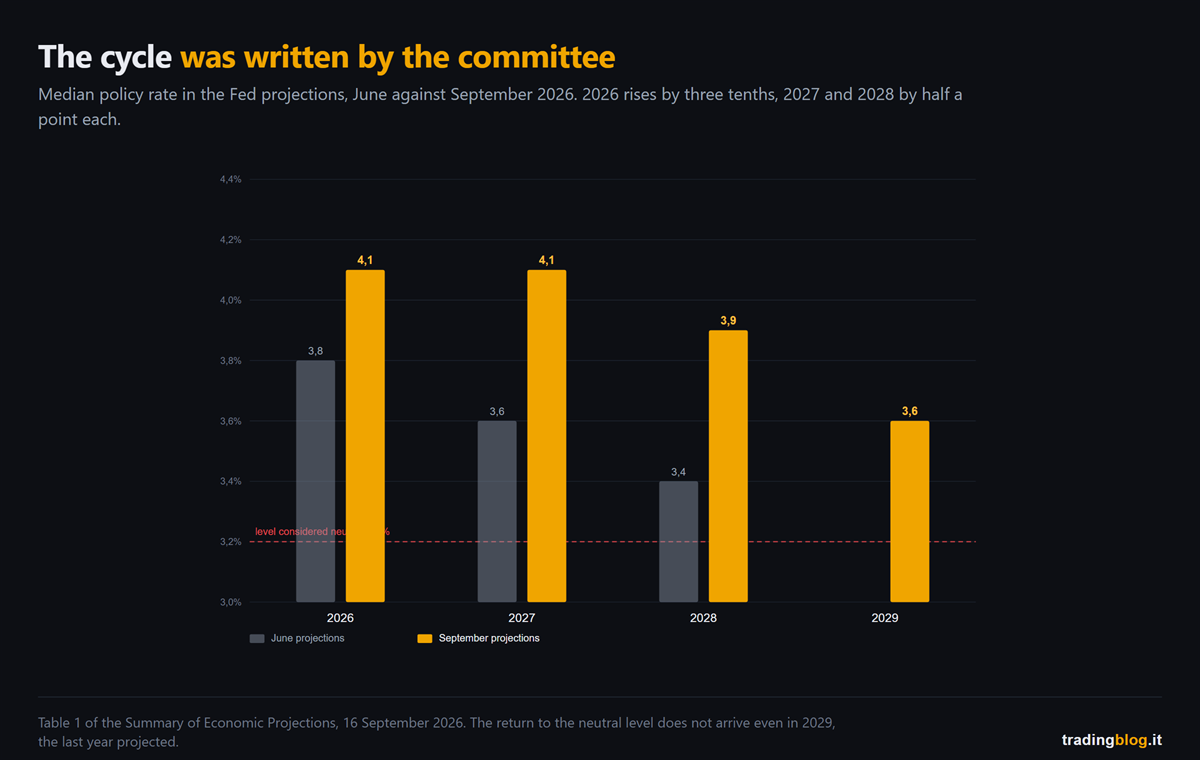
But look at what happened to the years after that, comparing the September projections with the June ones.

Bar chart comparing the median policy rates in the Fed projections from June and September 2026: every September bar is higher than its June counterpart, and none comes down to the line marking the 3.2% neutral level
The median rates in the committee’s projections, June against September 2026. 2026 rises by three tenths, 2027 and 2028 each rise by half a point.

The median for 2027 went from 3.6% to 4.1%. Half a point in three months.

The one for 2028 from 3.4% to 3.9%. Another half point.

And the trip back to the level they themselves consider neutral, 3.2%, never arrives at all. Not even in 2029, which is the last year projected: there the median does come down, but only to 3.6%.

Read it the way a trader would read it and not a journalist. The committee did not write “we hike once and then we see”. It wrote that rates go to 4.1% and stay there for two years, that in 2028 they come down to just 3.9%, and that at the end of the forecast horizon they have still not gone back to the level considered neutral.

That is not an isolated move. It is a high level held for years, written by the people who have to hold it. And in a moment you will see that the market expects even more than that.

And the market? It said they were right.

Here comes the part that flips your instinct.

When a central bank starts hiking, the script everyone expects is: equities down, volatility up, credit spreads widening, yields up all along the curve.

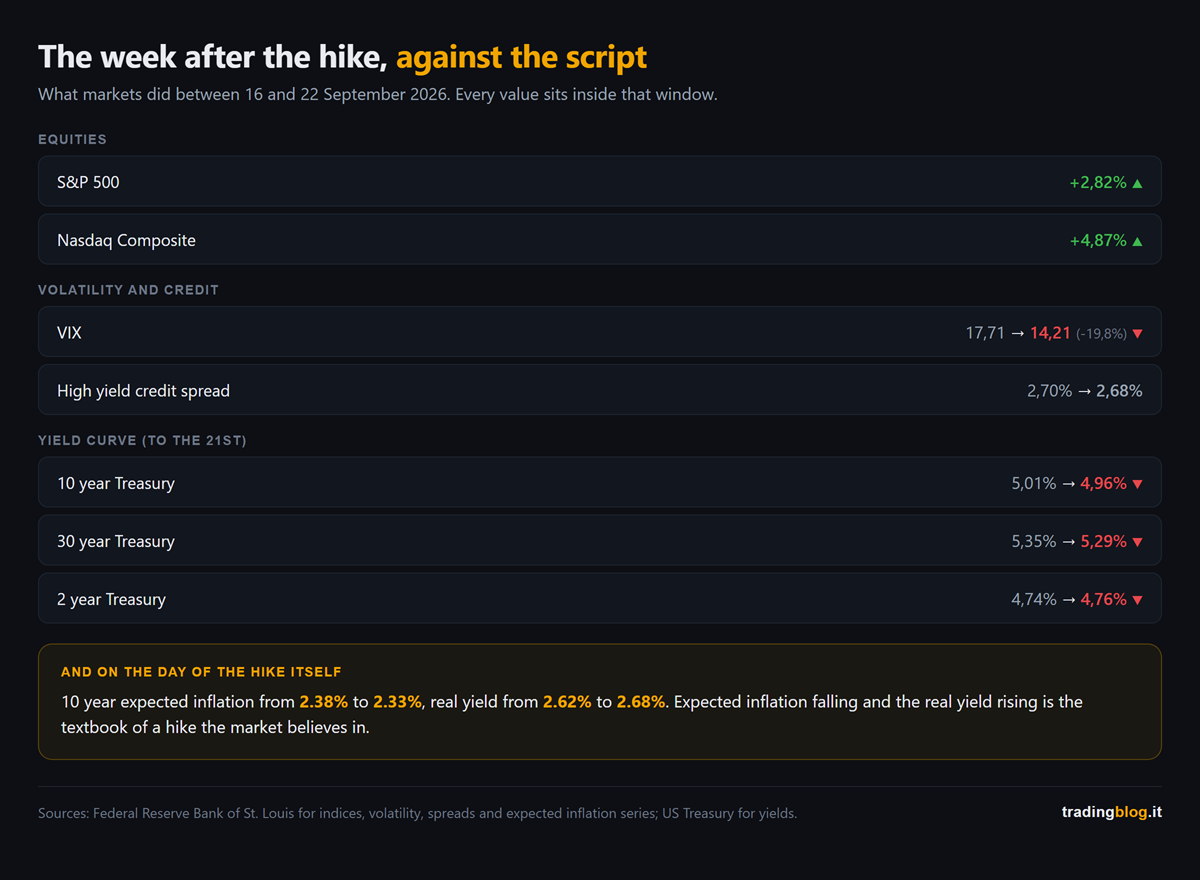
Between 16 and 22 September none of that happened. The numbers in this section sit inside that window, with two exceptions I flag as they come: the yield curve, which stops on the 21st, and the last data point, which measures the reaction of a single day.

Table of market moves between 16 and 22 September 2026: equities up, volatility sharply down, credit spreads almost flat, ten and thirty year yields down and the two year yield up
What markets did between 16 and 22 September 2026. Equities up, volatility down, credit spreads flat, and yields lower all along the curve.

The S&P 500 did +2.82% and the Nasdaq +4.87%, with a record high on the 21st and another on the 22nd.

The VIX went from 17.71 to 14.21, so minus 20%, at the lows of the month. Anyone selling volatility on the day of the first hike in three years was right.

High yield credit spreads did not widen by a single point: 2.70% on the day of the hike, 2.68% on the 22nd. A credit market that fears a squeeze does not sit that still.

And now look at the yield curve, where the data stops on the 21st because that is the last day published.

The two year went up, from 4.74% to 4.76%. The ten year went down, from 5.01% to 4.96%, and the thirty year from 5.35% to 5.29%.

Short end up, long end down: the curve flattened by seven basis points. And it is the same thing the earlier numbers say, put another way: the market expects more tightening now and less inflation later.

But the number that explains everything is another one, and it is the subtlest. This is the only one that falls outside the window, because it measures the reaction of a single day: it compares the close on the 15th with the close on the 16th.

On the day of the hike ten year breakeven inflation fell, from 2.38% to 2.33%, while the real yield rose from 2.62% to 2.68%.

And now the honest part, the one they usually do not tell you.

Ten year breakeven inflation is very sensitive to oil, and crude started falling exactly around those days. So a slice of that drop may be the barrel, not the Fed. Anyone selling you only the first half of the number is selling you a thesis, not a measurement.

But oil does not explain the other half. Crude falling pushes breakeven inflation down, it does not push the real yield up. Those six basis points of extra real yield on the very day of the decision are the one thing the barrel cannot account for, and that is where the thesis holds up.

Breakeven inflation down and real yield up, together, is what happens when the market believes the central bank will do its job. It is the textbook of the hike that works, not of the one that scares.

The market did not ignore the Fed. It believed it.

Where the market does not agree

There is one point where market and committee see it differently, and it is not the one you think.

On the next meeting, 27 and 28 October, futures gave 54% odds to another hike as of 22 September. A coin flip.

But looking out to December, the probability of being at least twenty-five basis points higher is 90%.

On direction they agree. The disagreement is on the when, and on the how much.

Over the next nine meetings fed funds futures were pricing, as of 22 September, around eighty basis points of total tightening, so roughly three hikes. The dot plot median forecasts one.

The market is pricing a longer cycle than the one the committee put on the dots.

And the two things I have just written do not contradict each other, they hold together: the market expects more hikes than the committee forecasts, and that is exactly why it expects less inflation.

What changes for anyone trading inside the day

This is the part that really concerns you, and it has nothing to do with forecasts.

The Fed chair, in the press conference, said two things that put together change the job.

The first: “I’m not in the forward guidance business”.

The second, explaining how he looks at the data: “data point dependence is a dangerous preoccupation”. Trends count, he said, single numbers are noise.

And he does not put his own dot on the dot plot, as he already did in June.

Translated into practice: the guidance the market had used for ten years to price meetings has been switched off by the people who issued it.

The market will keep pricing every single data point though, because that is what the market does. So the reactions to macro numbers are still there, and my expectation is that they get wider: with a central bank that refuses to guide, nobody confirms them or denies them the day after.

For anyone trading inside the day that is a concrete asymmetry: the move on the number is there, the confirmation that used to come afterwards is gone. You trade the reaction, not the anticipation, and to do that you need to know when the number lands.

The dates that really count

They are not all the same, and two of them weigh more than all the others put together.

Friday 2 October, the September jobs report. The committee projects unemployment flat at 4.1% for the next four years, so it expects no cost on the labour side. A weak jobs number is the thing most likely of all to change the committee’s mind from the inside. With one honest caveat: the standard the chair has set himself is declaredly about inflation, not about employment.

Wednesday 14 October, September inflation. It is the last consumer price print before the meeting on the 28th, and the chair said in the press conference that he builds his own estimates precisely on that one and on producer prices. It is the number that decides whether the next hike is in October or in December, and on that day the coin flip I mentioned above resolves one way or the other. The day after, on the 15th, producer prices come out, the second of the two numbers the chair builds his estimate with.

And be careful not to get confused: that number does not decide the committee’s mind, it decides the price. The chair has just said that he does not look at single numbers. The market does, and that is where the odds move.

Before those, on Wednesday 30 September, the August PCE comes out. It serves to check an estimate the chair made out loud in the press conference, and if it comes in above, the squeeze gets firmer.

And one to write down: the 28 October meeting has no dot plot. Statement and press conference only. The next update to the dots is in December.

A note on what can go wrong

The chair gave three reasons for the hike: an economy stronger than expected, inflation not coming down enough, and geopolitics.

The third has already moved, but not in the simple way. Crude had spiked all the way to 107 dollars on 15 September, the day before the decision, and from there it came back toward ninety, pushed by the diplomatic openings on Iran and by the expectation that Saudi Arabia will restart a major pipeline.

Watch out though: that is the unwinding of a spike, not a collapse. The barrel is still above late August levels. If it falls further, part of the job gets done by oil from the outside without the committee having to change its mind. If it climbs back up, it puts back in play one of the very reasons they hiked.

A note, because the week has already turned

What you have read above is the week from the 16th to the 22nd. On the 23rd the wind changed: equities came off the highs and the ten year yield went back up toward 5%, precisely on the fear of more hikes.

It does not disprove anything. If anything it confirms the more uncomfortable part: the market is not pricing less tightening, it is pricing more.

The circle we close

On 11 September, on this blog, we wrote that the number that decides the Fed is not the headline one but the core, and we argued it with the projections the ECB published the day before, where from 2027 onward core stays above the headline.

Five days later the Fed hiked, and its projections say exactly the same thing from the other side of the Atlantic: headline inflation coming back down first, core lagging behind, and rates that as a result stay high for longer.

Two central banks, same diagnosis. If you missed that piece, Friday’s CPI: the number that decides the Fed is not the headline is where this conversation started.

Breakeven inflation falling and the real yield rising is not a market ignoring the central bank. It is a market that believes it.

— tradingblog.itPosta su X

Let me close with the thing I wrote down in my notebook that evening.

For ten years we traded inside a system where, after every data release, somebody turned up to tell you how to read it.

That somebody has just said he will not be doing it any more.

It is not good news and it is not bad news. It is simply that noise now stays noise for longer, and the job goes back to being reading the reaction instead of waiting for the explanation.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.