
Posts

An isolated gas station on an empty desert road at night, its canopy lit and the price sign dark, with an amber glow on the horizon

Wednesday’s CPI: the headline will look scary, but the real risk is somewhere else

Hi trader,

the last time I wrote to you about a CPI, on 11 September, the market had the Fed hike at 70%.

And I told you that 70% was the worst place to be caught by a data release.

Five days later the Fed really did hike, the first hike in more than three years, rates at 3.75-4.00%.

This afternoon the September CPI comes out, and the picture has flipped.

The market now puts the end-of-month hike at around 20%.

And I’ll tell you right away why that worries me more, not less.

What comes out today, and when

The US September CPI, the consumer price index.

The Bureau of Labor Statistics publishes it on Wednesday 14 October at 8:30 am New York time, which is 13:30 in London and here in the Canary Islands, and 14:30 in Italy.

Here is what the market expects, compared with August:

What Expected September August
Headline CPI, year on year 3.6-3.7% 3.4%
Headline CPI, month on month +0.6% +0.4%
Core CPI (ex food and energy), year on year 2.4-2.5% 2.4%
Core CPI, month on month +0.2% +0.3%

On the core, the forecasts are bunched almost entirely around +0.2%.

Keep that in mind, because that is where the risk is hiding.

Oh, and tomorrow, Thursday, producer prices come out too.

So this afternoon does not close the story, it opens a two-day stretch.

Today’s headline will look scary

I’m telling you in advance, so you don’t get a fright at 8:30.

A +0.6% on the month would be the strongest monthly rise since April.

The reason is always the same: gasoline.

In August gasoline in the CPI was already up 27.4% on the year, and energy as a whole 16.3%.

In September gasoline rose again, and at the end of the month diesel hit its all-time record, just above 6.5 dollars a gallon as a national average.

Brent is trading around 105 dollars these days.

On Sunday Trump announced an “energy truce” between Russia and Ukraine, no more attacks on energy facilities.

Moscow did not confirm it, the attacks carried on, and on Monday oil closed higher instead of lower.

And the Middle East, which is what pushed the barrel all the way up there, has not calmed down at all.

In plain words: today’s headline is written by the barrel, and these days the barrel is written by the news from the front lines.

And that is exactly why the headline, for anyone who trades, matters less than it looks.

At the Fed almost everyone knows it’s gasoline.

The market knows it’s gasoline.

The phone notifications will talk about “inflation at a multi-month high”, and they will be right, but that is not the number the end-of-month game is played on.

August’s core was dirty

And here comes the part almost nobody tells you.

In August the core came out at +0.3%, above the +0.2% expected.

The market noticed right away: short-term yields went up, because a core above expectations is exactly what the Fed does not want to see.

But if you open the report and look inside, a slice of that +0.3% was not inflation spreading.

It was two odd items.

Phone services, up 5.4% in a single month because of price hikes and plan changes at AT&T and T-Mobile, added about a tenth of a point to the core on their own.

And hotels, +2.4% after two months of similar declines, which is a rebound more than a trend.

Take those two things out and August goes back to being a normal month.

That is why almost everyone expects a September core at +0.2%: not because inflation is cooling, but because those two items don’t repeat.

It’s like a puncture in qualifying.

The lap time is bad, but it tells you nothing about race pace.

So what do I look at inside today’s core?

One item, before all the others: airline fares.

Because a plane ticket is a service, but there is fuel inside it.

In August flights were already up 23.4% on the year: the barrel has been passing from fuel into services for months, and the question is whether it speeds up.

That is still an indirect effect, fuel going into the price of a service.

The next step is the one the ECB had put into its projections in September, the second-round effect: wages and price lists adjusting.

That is where the price rise stops being gasoline and becomes something else.

Why this time the risk is all on one side

Back to that 20%.

How did we get there?

Up to 28 September the market had the end-of-month hike at around 70-75%.

Then in four days three things happened.

On 29 September John Williams, the president of the New York Fed, said there is no urgency and that another move could come towards the end of the year.

The October odds collapsed right there.

The next day August PCE, the index the Fed actually uses for its 2% target, came out a touch below expectations.

And on 2 October the September jobs report came out very weak, 29,000 jobs against an estimate of around 90,000, unemployment up from 4.1% to 4.2%.

Result: October almost priced out, and the whole bet moved to December, where a hike is priced at around 85%.

So the story the market has told itself is this: October on hold, December hike.

Now think about how a price built like that reacts.

If the core comes out at +0.2% today, the market says “I knew it”.

Movement, sure, but inside a script already written.

If it comes out at +0.3% or higher, above almost every forecast, that 20% for October is no longer a 20%.

And a bet that has to be repriced from 20 to 50 in one afternoon is far more violent than one going from 70 to 80.

In September the hike was in the price, and the data could only confirm it or disappoint.

Today the hike is almost priced out, and only one surprise really hurts.

There is also the opposite tail, and it’s not one to dismiss.

Core at +0.1% with a labour market creating 29,000 jobs, and someone at the table will start asking whether December is really needed.

The 85% for December would deflate, and that really would be a field day for equities.

Less likely, but possible.

My point is a different one: the market is leaning on a single story, and the dangerous afternoons are the ones when the story breaks.
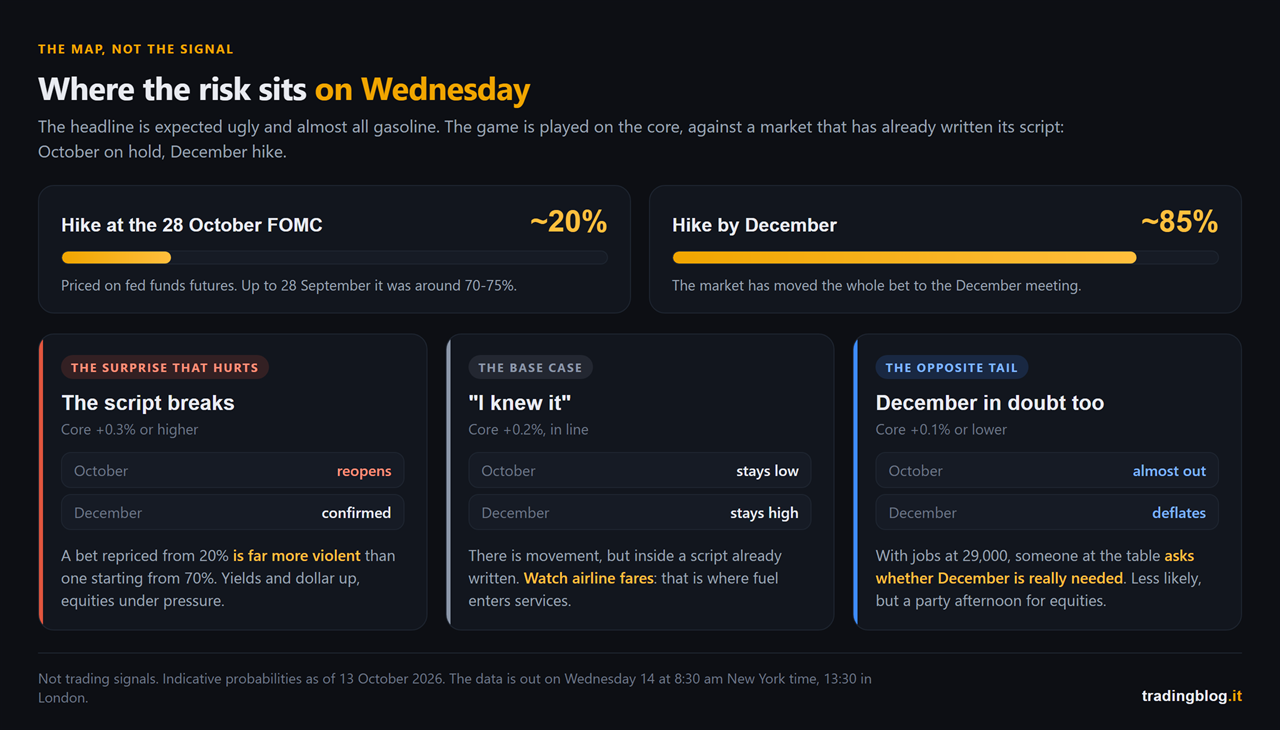
Diagram of where the risk sits on the September CPI: a Fed hike in October priced around 20% and in December around 85%, and what a core print of +0.3% or higher, +0.2%, or +0.1% or lower tends to move
Where the risk sits on Wednesday. With the October hike priced at around 20% and the December one at around 85%, here is what each core outcome tends to move. These are not signals, it is the map.

A Fed pulled two ways

There’s one last thing that makes this CPI different from September’s.

In September the Fed had one problem: inflation.

Now it has two, and they pull in opposite directions.

On one side prices rising because of energy, with the US 10-year above 5% and the president of the Cleveland Fed, Beth Hammack, saying rates need to be higher because inflation is broadening.

On the other a labour market that this year has created 68,000 jobs a month on average, and that in September created less than half of that.

The minutes of the September meeting say the committee sees another hike by the end of the year.

They don’t say when.

And when a central bank doesn’t say when, the data decides.

Today is the data.

How I handle it

The rules are the usual ones, because CPI days all look alike.

I don’t enter on the 8:30 spike.

First the market reads the headline, which today will be ugly and already expected.

Then it reads the core.

Then, if it’s someone who works properly, it opens the detail and looks at what’s inside.

The move that holds until the evening is almost always born at the second or third pass, not the first.

I show up with the map already drawn.

Calendar, levels, and where the options market has its walls on the S&P and the Nasdaq.

On a day like this part of the move is made by market makers hedging, not by the news, and that’s gamma exposure.

I check it on the Thunder Desk, which is free and puts the macro calendar and gamma on the same screen.

The point isn’t the tool, it’s opening it in the morning, not at 8:29 with the position already open.

I cut size before, not after.

If a position is still alive at 8:30, the spread can widen and the stop can get filled a few ticks further away.

What that scenario really costs me I work out now, with numbers, not by eye.

And I log the reaction, not the result.

What I expected, what came out, what price did in the first five minutes and what it did by 10 am.

Do it today, and do it again at the end of the month with the FOMC.

A few days like this in the diary and your recurring behaviour around macro data shows up on its own.

Three takeaways

  1. Today’s headline will be ugly, and it’s already written. Headline expected at +0.6% on the month and 3.6-3.7% on the year, almost all energy, meaning gasoline. That’s not where October is decided.
  2. August’s core was inflated by two items that don’t repeat. A +0.2% today doesn’t mean inflation is cooling, and inside it airline fares are worth watching, the point where the barrel enters services.
  3. The market has already decided: October on hold, December hike. With October at around 20%, the surprise that hurts most is a core at +0.3% or higher. You don’t need to guess it, you need to know beforehand what you do if it comes.

If you missed the previous episodes, the piece on the August CPI is where the headline versus core discussion started, and the piece on the September hike explains why from here on every inflation print weighs double.

The dangerous number is not the one the market fears. It’s the one the market has stopped fearing.

— tradingblog.itPosta su X

I’ll close with what I tell myself every time I see a calm market before a release.

Calm doesn’t mean safe.

It means everyone has bet on the same story.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.

An oil tanker in the dark on a black sea, backlit by an amber glow on the horizon

Friday’s CPI: the number that decides the Fed is not the headline

Hi trader,

yesterday afternoon the ECB raised rates.

Second hike of the year, deposit rate at 2.50%, effective from 16 September.

And the curious part is the reason why.

Not because the European economy is running hot, it is growing 0.9% this year, which is barely more than nothing.

It hiked because the war in the Middle East keeps pushing on prices, and because that increase has stopped being just energy.

Let me walk you through it properly, because it is exactly the same question America will be asking itself on Friday afternoon.

What comes out on Friday, and when

It is the US CPI for August, the consumer price index.

The Bureau of Labor Statistics publishes it on Friday 11 September at 8:30 am New York time, which is 1:30 pm here in the Canaries and in London, and 2:30 pm in central Europe.

There are two numbers inside it, and most people only look at one.

What August forecast July (released 12 Aug)
Headline CPI, year on year 3.3% 3.4%
Headline CPI, month on month +0.4% +0.1%
Core CPI (ex food and energy), year on year 2.4% 2.5%
Core CPI, month on month +0.2% +0.2%

The headline is the big number, the one that shows up in your phone notifications at 8:30 and one second.

The core is the same index without food and energy, which are the two components that swing the most.

It sounds like a detail for economists.

It is the detail that decides what the Fed does next Wednesday.

One clarification that matters, because almost nobody spells it out: the Fed does not measure its 2% on the CPI, it measures it on the PCE, which comes out two to three weeks later.

Friday’s CPI is the first taste, and it is the one the market moves on.

But keep the number in mind: in July the CPI was at 3.4% and the PCE, the index the Fed actually watches, at 3.7%.

Why the big number lies this year

Look at the forecasts in that table.

Headline monthly going from +0.1% to +0.4%, so four times as much.

And meanwhile the annual headline goes down, from 3.4% to 3.3%.

Core moving by one tenth instead, from 2.5% to 2.4%.

If Friday comes out like that, the message is not “US inflation is taking off again”.

The message is “US inflation is being made by the barrel”.

Brent above 100 dollars, a 4% jump yesterday that took it into the 105 area on yet another attack on commercial shipping, pump prices following in stages, half the increase within two weeks and the rest over the month and a half after that.

And it is not just a forecast any more.

Yesterday US producer prices for August came out at +5.4% year on year, and more than three quarters of the monthly increase is energy: +4.2% in thirty days, with diesel at +24%.

Producer prices are the floor above, the one the consumer sees a few months later.

This is called cost-push inflation, inflation that comes from the supply side.

It does not come from people buying too much, it comes from something costing more because getting it here has become complicated.

And there is very little a central bank can do about inflation that comes from the supply side.

Raising rates does not reopen a strait and does not make a tanker arrive any sooner.

The old textbook says a central bank should “look through” a supply shock, because it fades when the shock fades.

The problem is that the textbook holds only as long as that increase stays locked inside energy.

The detail the ECB put right in front of you yesterday

And this is where yesterday becomes useful, instead of just being an item on the evening news.

Look at the projections the ECB published yesterday, the ones from its own staff:

Year Headline inflation Core inflation
2026 3.0% 2.5%
2027 2.5% 2.6%
2028 2.1% 2.3%

Did you notice?

In 2027 and 2028 the ECB expects core to be higher than the headline.

And there is one more detail: it revised that 2027 and 2028 core up by a tenth compared with June.

It does not just expect the second round, it expects it a shade stronger than it did three months ago, and it puts that down to an economy holding up better than forecast and to wages growing a little faster.

Translated: it expects energy to come back down, and it expects that by then the increase will already have passed into everything else.

Transport costing more, so goods costing more, so services, so wages asking to catch up.

They are called second-round effects, and they are the only thing that justifies a hike in the middle of a war.

It did not hike because of the barrel.

It hiked because the barrel is getting into places it does not come out of.

Lagarde said two things in the press conference worth keeping: that this hike was “a no brainer”, an obvious call, and that she cannot anticipate what the next move will be.

No commitment to a rate path, decisions taken meeting by meeting.

The exact same words you will hear on Wednesday from the other side of the Atlantic, want to bet?

Why Friday carries more weight than usual

Because the Fed decides on 16 September.

Two-day meeting, the 15th and the 16th, decision on Wednesday afternoon, and this time there is also the dot plot.

The dot plot, let me explain, is that chart of dots where each of the people sitting at the table, including the ones who do not vote this year, marks where they see rates at the end of this year and in the years after.

Nobody signs their own dot, so nobody really commits, but the cloud of dots tells you which way the wind is blowing inside the room.

It comes out four times a year. The last one was in June. The next one is Wednesday.

And it lands at an unusual moment.

US rates have been sitting at 3.50-3.75% for five meetings.

In July three members voted against, and not to ask for a cut: to ask for a hike.

Then on 28 August, at Jackson Hole, Fed Chair Warsh talked about credibility and about a 2% target with no discounts, and the odds of a September hike almost doubled in three days, from 35% to 66%.

And yesterday the market changed its mind in half an hour.

That producer price print pushed the bet on Wednesday’s hike from about 60% to about 70% on futures, and prediction markets toward 63%.

That is why Friday is not just another data point.

It is the last inflation print before a decision that is already half priced, but not closed.

And a market at 70% is the worst place to be caught by a data release: the hike is in the price enough not to pay you if it lands, but not enough to protect you if it does not.

And afternoons where one number can still move a decision that is already half written are the afternoons when the chart does not forgive a lapse in attention.

The four roads the afternoon can take

I am not giving you entry signals, of course not.

I am giving you the map, so that whatever comes out at 8:30 does not catch you open-mouthed.

Hot headline on the month, cool core. The consensus scenario. This is the “it is all fuel” case: the Fed can say it is letting that increase pass through, the hike bet deflates a little, yields take a breath and equities get some air. Careful though, it is relief with an expiry date stamped on it, because with Brent up there the same question comes straight back next month.

Hot headline, hot core. The worst one if you hold bonds and equities. It means the barrel is already inside the rest of the basket, exactly the scenario the ECB put in writing for Europe yesterday. Here Wednesday’s hike becomes the main bet, the dot plot shifts up, the 10-year, which yesterday was trading around 4.9% and sits at its highest since late 2023, goes looking for the next threshold and equities pick up the bill.

Headline in line, core below forecast. The best one for equities. The hawks are left without ammunition for a week and the market celebrates. It is also the scenario where it is easiest to fall in love with the move and stay long into Wednesday, which with a dot plot on the way is an elegant way of giving the profits back.

Everything below forecast. The hike prices out, and the old “weak data, kind central banks, buy everything” reflex is back. But watch out: this Fed chair has built the first months of his term on the credibility argument. A good print does not change his problem, it postpones it.

Diagram of the four combinations of headline and core CPI, with the market's typical reaction in each case
The four combinations of headline and core, and what the market tends to do in each one. These are not signals, they are the four ways the afternoon can go.

How I handle it

Three practical things, all of them learned the expensive way.

I do not enter on the spike.

I do not trust the first candle at 8:30, and not for psychological reasons so much as technical ones: wider spreads, slippage, prices going one way and coming straight back in the time it takes you to read the headline.

The market reacts to the big number first, then reads the core, and only then really makes up its mind.

In my diary, the move that holds into the close is almost never the first one.

I look at where the walls are before the number is out.

On a day like this, part of the move is not made by the news, it is made by the levels where the market is already loaded with options and market makers have to hedge.

That is not black magic, it is gamma exposure, and knowing where those levels sit changes how you read a spike.

The macro calendar and the gamma on the S&P and the Nasdaq are on the Thunder Desk, they are free, and they spare you the classic scene of a trade left open by accident thirty seconds before the release.

Open it in the morning, not at 8:29.

I cut size before, not after.

If you have a position going into Friday afternoon alive, you do the maths now on what you actually lose if the stop goes with a double spread, with numbers, not by eye.

And I write everything down.

Not the result, the reaction: what I expected, what came out, what price did in the first five minutes and what it did at 10 am.

After three or four macro releases logged in the diary you start noticing that you, personally, have a recurring behaviour on days like these.

It is almost always the same mistake, and it is almost always an expensive one.

Three things to take home

  1. Friday’s big number and the number that moves the Fed are two different numbers. Monthly headline expected to accelerate hard on energy while the annual one falls. Core expected to sit still. It is the distance between the two that tells you whether this inflation is a barrel of oil or something deeper.
  2. The ECB showed you the criterion yesterday. It hiked looking not at the headline but at a core that in its own projections stays above the headline in 2027 and 2028. When a central bank fears second-round effects, the hike arrives even in the middle of a war and with growth at 0.9%.
  3. Wednesday brings the dot plot, and the hike is already 70% priced. An inflation print landing five days before a decision that is almost made but not signed is worth double the usual. You do not need to guess it. You need to not be surprised by it.

If you want the wider picture, the piece on what was at stake at the Fed at the end of July and the one on what a strong dollar does to your trades still hold up, the context has changed less than it looks.

The headline tells you what fuel costs. The core tells you whether the problem is the fuel or you.

— tradingblog.itPosta su X

Let me close with the thing I repeat to myself every time there is a big release on the calendar.

My job on Friday at 8:30 is not to guess the number.

It is to know in advance what I do in each of the cases, and to have already decided which of those cases keeps me out of the market.

The rest is noise.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.
