Posts

The trader of the future with the amber and violet visor looks at a monumental glowing vault door which, seen from the side, turns out to be a paper thin panel standing on nothing, with emptiness behind it

The exchange: where you buy, and what happens if it goes down

Hi trader,

last lesson we left off on a sentence that now needs explaining properly: on an exchange the keys are theirs.

If you missed the earlier pieces, keys and wallets is what you need to make sense of this one.

Today we look inside the box. What an exchange actually is, what happens when you click buy, and what happens to your money the day it shuts down. Because it is not a theoretical scenario: it has already happened, more than once, and people lost everything.

Ok, vamos.

The thing almost nobody has clear

An exchange is not the blockchain.

It is a company. With servers, employees, a legal department and, above all, a database.

And that is not a pedantic distinction, because it has an enormous consequence: when you buy on an exchange, nothing happens on the blockchain.

Zero. No row gets written on the public ledger. No network fee. No confirmation to wait for.

Two numbers change in their database: the euro one goes down, the bitcoin one goes up. And the bitcoin it shows you are not “yours”: they are a share of a pile the exchange keeps for all its customers together, and it holds the keys.
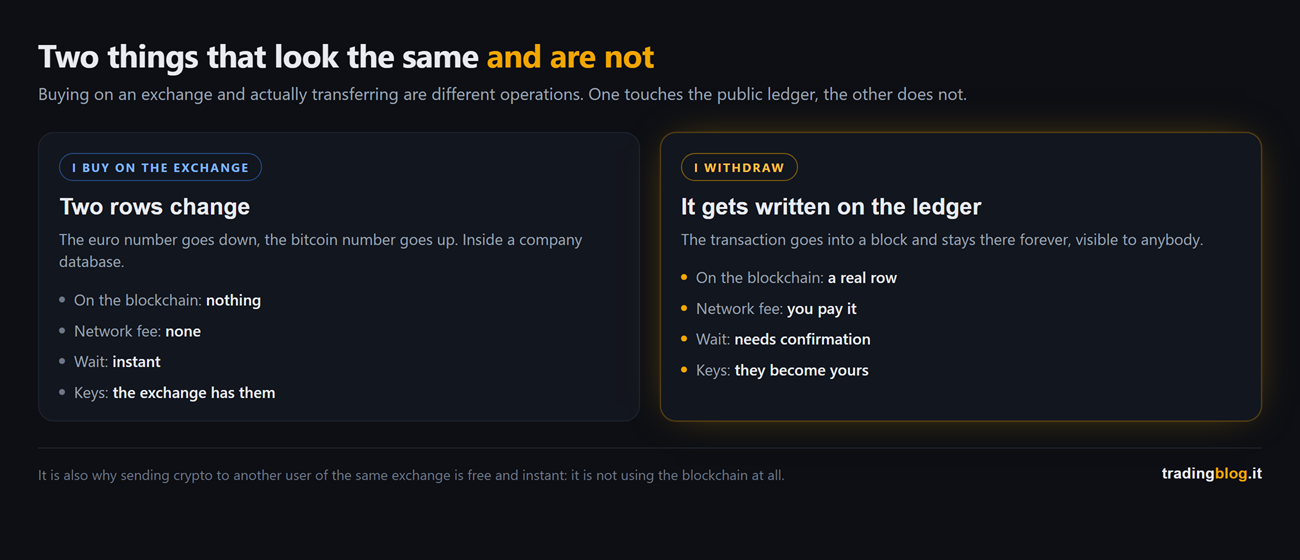
Comparison between buying on an exchange, where only two rows change in the company database without touching the blockchain, with no fee and no wait but the keys held by the exchange, and withdrawing, where the transaction is actually written on the public ledger, the network fee is paid, confirmation is needed and the keys become yours
The two things that look the same. On the left a purchase on an exchange: two rows change in the company database, the blockchain never notices. On the right a real transfer: the row gets written on the public ledger, with a fee and a confirmation time.

Inside, though, it is a real market

And this is where it gets interesting for somebody who trades, because you already know the mechanism.

Inside the exchange there is an order book, exactly like on futures: a list of who wants to buy and at what price, and who wants to sell and at what price.

And there are the two ways of being in the market we covered in the order flow series: there is the one who places a limit order and waits at their price, and the one who sends a market order and pays to get in now.

If that feels familiar it is because it is: it is the exact same dynamic as bid/ask candles, aggressive against passive.

There is also a practical detail worth money, and it has to be stated precisely because it gets told badly out there.

Many exchanges apply two different fees: a lower one for whoever adds liquidity to the book and a higher one for whoever removes it. The jargon calls them maker and taker.

Careful though, because they do not coincide with limit and market. If you place a limit order inside the spread, it executes immediately against the book and pays the expensive fee, exactly like a market order. You only get the cheap fee if your order sits there waiting and somebody else executes against it.

And it is not a universal rule either: on some exchanges, including the most used one in the world, the two fees at base tier are identical, so that advantage does not exist at all. On others the gap is double. Go and look at your own fee table, it is a boring page that tells you what you are actually paying.

Why sending to another user is free

This also explains something that confuses a lot of people.

If you send crypto to somebody on the same exchange, it is often instant and costs nothing. If you send it out, you pay and you wait.

By now you know why: in the first case you are not using the blockchain at all. Two rows are just changing in their internal database, which costs them nothing.

In the second case the transaction really does have to be written on the ledger, and that is where you pay.

Custodial, and what it means for you

The exchange holds everybody’s keys, and it keeps them in two places: some in vaults connected to the internet, so it can serve withdrawals quickly, and most of it in vaults kept offline, far harder to drain.

As long as everything works, this does not concern you at all.

The day it stops working, this is the only thing that concerns you.

What happens if it goes down

Here we get to the serious part, and I will say it without dancing around it.

You are not a depositor. In practice you are much closer to a creditor.

When a bank fails, in Europe there is a deposit guarantee up to a hundred thousand euros. On an exchange that safety net does not exist: no guarantee fund, no compensation scheme, and it is not me saying it, it is the European authorities themselves in a consumer warning.

The European rules that came into force in recent years did introduce a real protection though, and it would be dishonest to leave it out: anybody authorised in Europe is required to keep client crypto separate from its own, so that its creditors cannot get their hands on it if it fails.

It is serious protection, and it did not exist before. But it depends on two things: that the provider really is authorised in Europe, and that it really did follow the rules. If it did not, you find out on the day of the collapse, and at that point you join the queue and wait for a court to decide who gets what, and over how many years.

Outside Europe there is often not even that. In the United States, in 2023, a judge ruled that the crypto deposited by customers of a failed platform belonged to the company and not to them: those customers ended up in line like every other creditor.

And it is not theory.

Mt. Gox, which in 2014 handled most of the world’s bitcoin trading, collapsed losing hundreds of thousands of customer bitcoin. Creditors waited more than ten years to see part of their money again.

FTX, in November 2022, was one of the three largest exchanges in the world, with sports sponsorships and famous faces. It collapsed in a week when it came out that customer money had gone where it should not have. The founder was convicted.

Neither of them looked at risk the day before. That is exactly the point.

And now the detail that can actually save you

When these things happen, the site does not shut down. Something sneakier happens: first they freeze withdrawals, and only then comes the bankruptcy. In between there are days or weeks in which your balance is right there on the screen, you can see it, and you cannot touch it.

It is not an impression, it is the documented sequence of every 2022 collapse: withdrawals frozen on 8 November, bankruptcy filing on the 11th. Another platform froze in June and failed in July, a month later.

So if one day you read that an exchange has “temporarily suspended withdrawals for maintenance”, that is not maintenance. It is the last warning, and it usually arrives when it is already late.
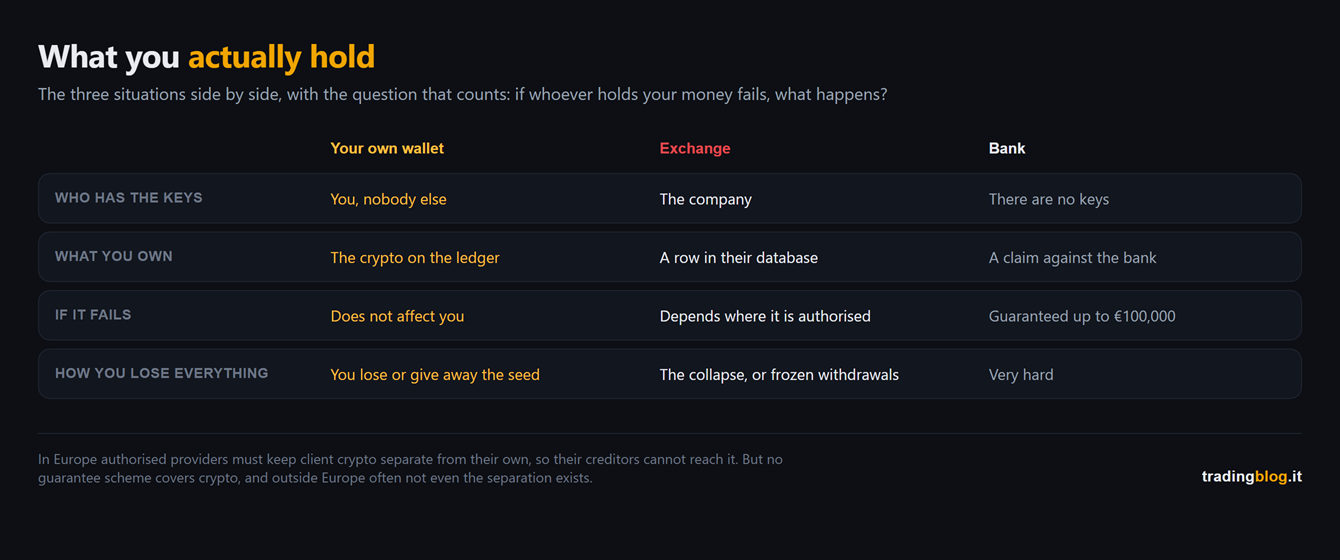
Table comparing a personal wallet, an exchange and a bank across four rows: who holds the keys, what you actually own, what happens if whoever holds the money fails, and how you can lose everything
What you actually hold in the three cases: crypto in your own wallet with your own keys, crypto on an exchange, money in a bank. For each one who holds the keys, what you legally own and what happens if whoever holds it fails.

How to choose one, and how to sit on it

I will never tell you which one to use, and be wary of anybody who does it lightly, because they almost always have an affiliate link in their pocket.

Here are the criteria.

Look at where it is regulated. Europe now has a framework of rules for anybody offering crypto services, and we covered it when it came into force, in the piece on MiCA and stablecoins. A provider authorised in Europe is not bulletproof, but it has obligations that one registered on an island does not.

Proof of reserves is not a promise of solvency. Many exchanges publish a check showing how much they hold. Careful though: it shows what they own, not what they owe, and at one precise instant. A company can have the reserves and have debts bigger than the reserves. It is useful, it is not a guarantee.

Turn on two step verification, but with an app, not with SMS. A phone number can be stolen by convincing the mobile operator to move it to another SIM, and it is a scam that has been going on for years.

And above all: keep on the exchange only what you need to operate. The rest you take out, where the keys are yours. This is the practical consequence of all three lessons so far.

Two clarifications though, because people make two opposite mistakes with this advice.

The first: it does not only apply to bitcoin. The balance almost everybody leaves sitting on an exchange is in euros or stablecoins, and the reasoning there is identical, with the added risk of whoever issues the stablecoin. Taking your crypto out and leaving the bulk inside in stablecoins is not securing anything.

The second: taking it out moves the risk, it does not delete it. Outside, the keys are yours, and so are the ways of losing them we saw last week. If you throw away the recovery phrase, there is not even a queue at the courthouse.

What you do from tomorrow morning

Two things, and the first one is a calculation that takes a minute.

Look at how much you have on the exchange and ask yourself: if they shut the site tomorrow morning, would this amount ruin me? If the answer is yes, that amount is too high, no matter how reliable the company seems to you.

Then make a small withdrawal to your own wallet. Not to move the money: to learn the procedure with pocket change, when you are not in a hurry and not scared. The day you actually want to do it will probably be a day when everybody is withdrawing at once, and that is not a good moment to learn.

And since it is the only irreversible thing I am asking you to do, three hard rules while you do it. Copy the address from the wallet, do not type it by hand. Check that the network selected on the exchange is the same one your wallet expects, because sending on the wrong network is the number one way money disappears on a first withdrawal. And after pasting, read the first and last characters again: there is malware that swaps the address in your clipboard while you copy it.

Where we go next time

So far we have talked about infrastructure: the ledger, the keys, the place where you buy. Next time we move on to what is inside, and to the first distinction that matters: bitcoin and ethereum are not two versions of the same thing, they are two different jobs.

On an exchange you do not have the keys. You have a company’s promise to give you your crypto when you ask for it.

— tradingblog.itPosta su X

Let me close with the thing that convinced me to take out the money I do not use.

It was not fear of a collapse, and it is not distrust of any company in particular.

It was a question I asked myself looking at the screen: if this site does not open tomorrow, what do I have in my hands?

The answer was: a screenshot. And the screenshot is not yours.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.

Bundle of amber light streaks hurled at high speed against a dark stone monolith that does not move an inch, the streaks bursting into sparks against its face while a few pass beyond it into the dark meeting nothing

CVD does not tell you who is buying. It tells you who is in a hurry.

Hi trader,

when I closed the order flow series I left one thing hanging.

I said that CVD, if we ever talked about it, deserved a piece of its own.

Here it is. And it is the one where I risk annoying you the most, because it touches the indicator everybody sticks under their chart and almost nobody reads for what it is.

Let me tell you straight away how I used it badly myself, so we get that out of the way.

I had put it under the price and I was drawing divergences on it the way I used to draw them on the RSI ten years earlier. I found dozens of them. You will find dozens too, if you do that.

After a few months the conclusion I had reached was that order flow does not work.

The right conclusion was a different one: I was using a measuring instrument as if it were an oscillator.

Ok, vamos.

The arithmetic, in three lines

In the first episode we opened the candle up and saw that every fill has a side: there is the one who was waiting with a resting order, and there is the one who went and took it, paying the spread.

Delta is the difference between those two, bar by bar: buy aggression minus sell aggression.

CVD, meaning cumulative delta, is the same thing summed over time. A line that rises when the hurry to buy is in charge, and falls when the hurry to sell is.

That is all. There is nothing else inside it.

And now the sentence that changes everything

CVD does not measure how many are buying and how many are selling.

It cannot, and this is arithmetic, not opinion: in every single trade the quantities bought and sold are identical by definition. If somebody bought ten contracts, somebody else sold them ten. Always. There is no such thing as a candle where “they bought more than they sold”.

What is not identical is which of the two was in a hurry.

So:

CVD measures who is in a hurry, and which side they are on.

Read that again, because everything else in this piece descends from that line, mistakes included.

The right way to read it: it is the effort, not the result

If CVD is the hurry, then it is the effort. And price, which is the result, sits on the other side of the scale.

Taken on their own they say almost nothing.

They matter when they do not add up.

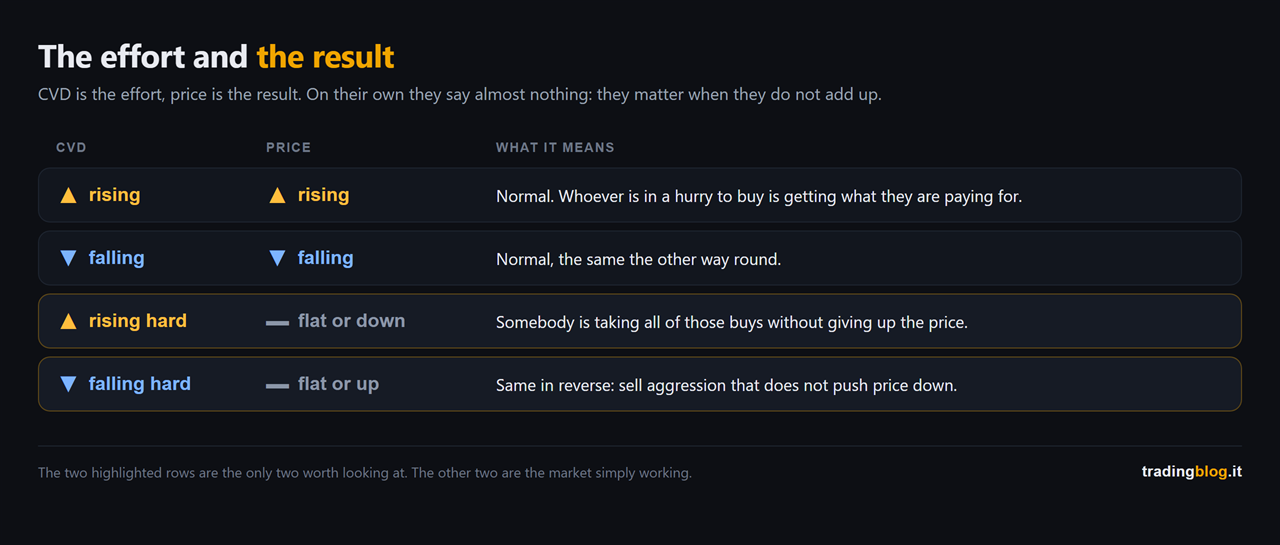
Table crossing CVD and price: when they rise or fall together there is nothing to read, while the two highlighted rows are the ones where CVD runs hard and price stays flat or goes the other way, meaning somebody is absorbing
The matrix between CVD and price. When they rise together or fall together there is nothing to read. When CVD runs hard and price does not move, or goes the other way, somebody is absorbing on the other side.

Look at the two highlighted rows in the figure, because they are the only two that count.

Lots of people in a hurry to buy, and price not going up.

At that point the right question is not “who is buying”. The question is: who is on the other side taking all of them?

The three reasons a divergence appears

And here we get to the part that makes reading this far worthwhile.

Price makes a new high, CVD does not. The famous divergence. On the internet they sell it to you as the signal that gets you the high of the day.

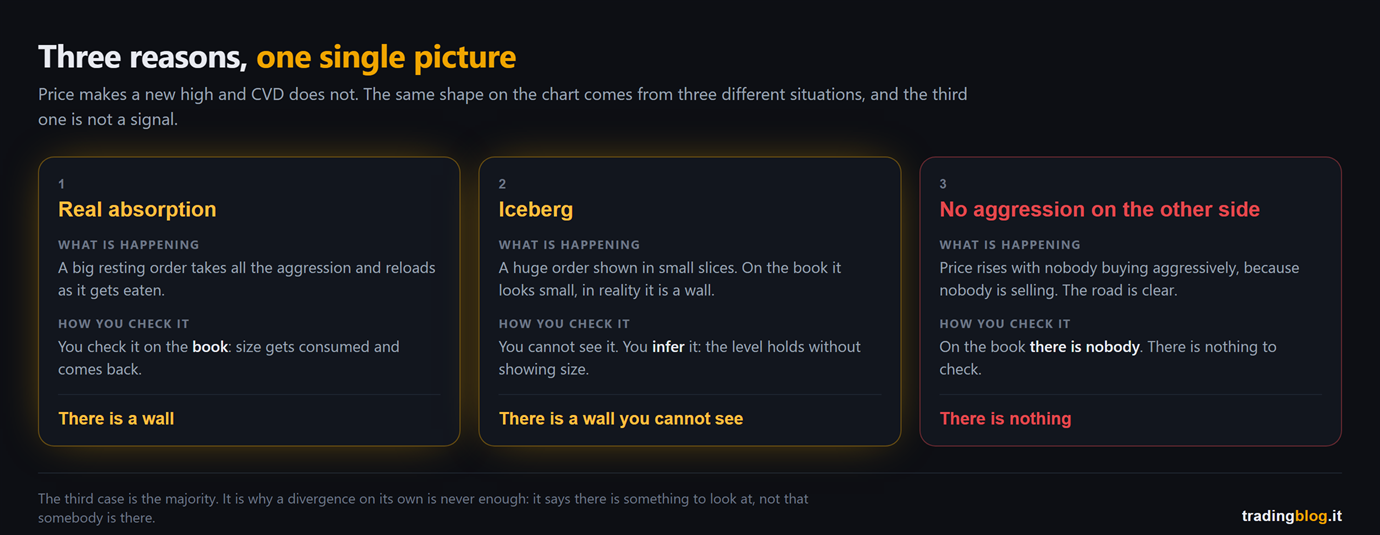
The problem is that the very same picture comes from three different situations, and only the first two are interesting.

One, real absorption. There is a big resting order sitting there taking all the aggression and reloading as they eat it. That is the one we care about, and it is the one we covered in the second episode. You check it on the book, not on CVD.

Two, the iceberg. A huge order shown in small slices. On the book it looks small, in reality it is a wall. Same dynamic as the first, except you cannot see it: you infer it from the fact that the level holds without showing size.

Three, and this is the one nobody tells you about: there simply is no aggression on the other side.

Price rises, CVD does not rise, and not because somebody is absorbing.

It rises because there is nobody selling.

The sellers got out of the way, the road is clear, and price drifts up without anyone having to pay to carry it there.

The three reasons a divergence between price and CVD appears, side by side: real absorption which you check on the book, an iceberg which you infer because the level holds without showing size, and simply no aggression on the other side, where there is nobody on the book and nothing to see
The three reasons a divergence appears, side by side: real absorption, iceberg, and simply no aggression. The first two get checked on the book, the third one is not a signal of anything.

That third one is the majority of cases, and it is why a divergence on its own is never enough.

Because the first two say “there is a wall”. The third says “there is nothing”.

And on the chart, under the price, they have exactly the same face.

A case of mine, and the mistake I made with it

ES, 6 August, two screenshots ten minutes apart.

I am telling you about it because I got this wrong first, and the mistake is exactly the one this piece is supposed to teach you to avoid.

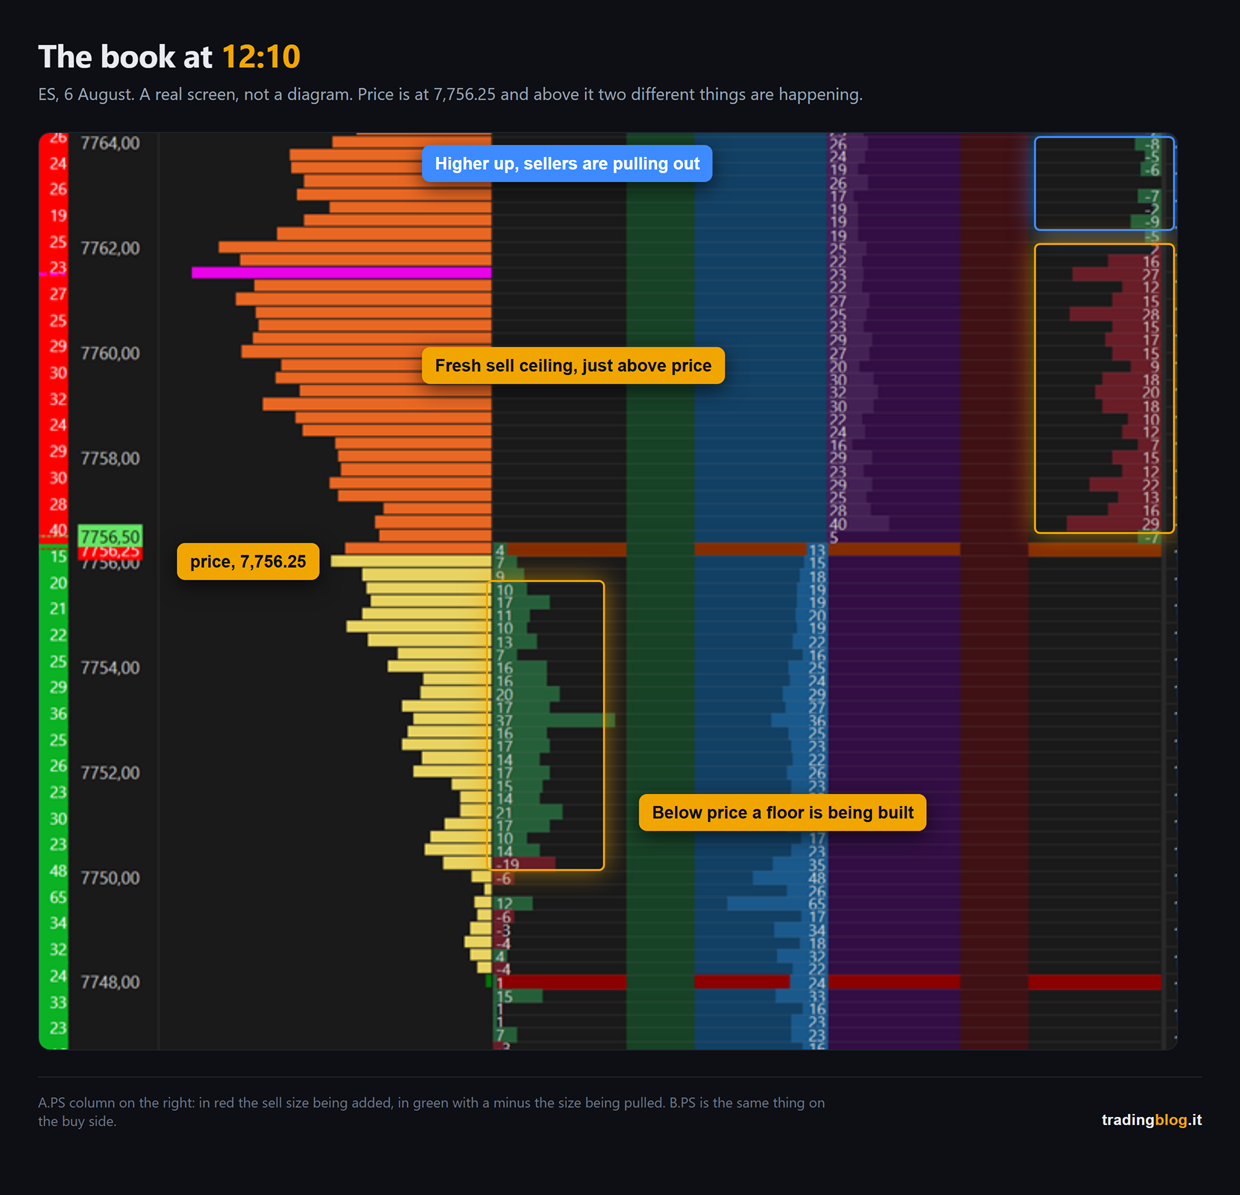
At 12:10 price was at 7,756.25, with the book showing a fresh ceiling of sell orders just above, and further up the sellers pulling themselves out of the way.

Real screenshot of the ES order book on 6 August at 12:10, price at 7,756.25: in the A.PS column the fresh sell ceiling just above price, higher up the sellers pulling their size, and below price the floor being built in the B.PS column
ES, 6 August, 12:10. The real book: at the top the sellers pulling out, just above price the fresh sell ceiling, and below it the floor being built.

At 12:20 price was at 7,760.25. The ceiling had not held.

Ten points of upside. And underneath, cumulative delta was reading -239.

My first read was this one: CVD is negative, so nobody is buying aggressively, so that rise is not a push, it is a void.

It sounds good. And it is wrong.

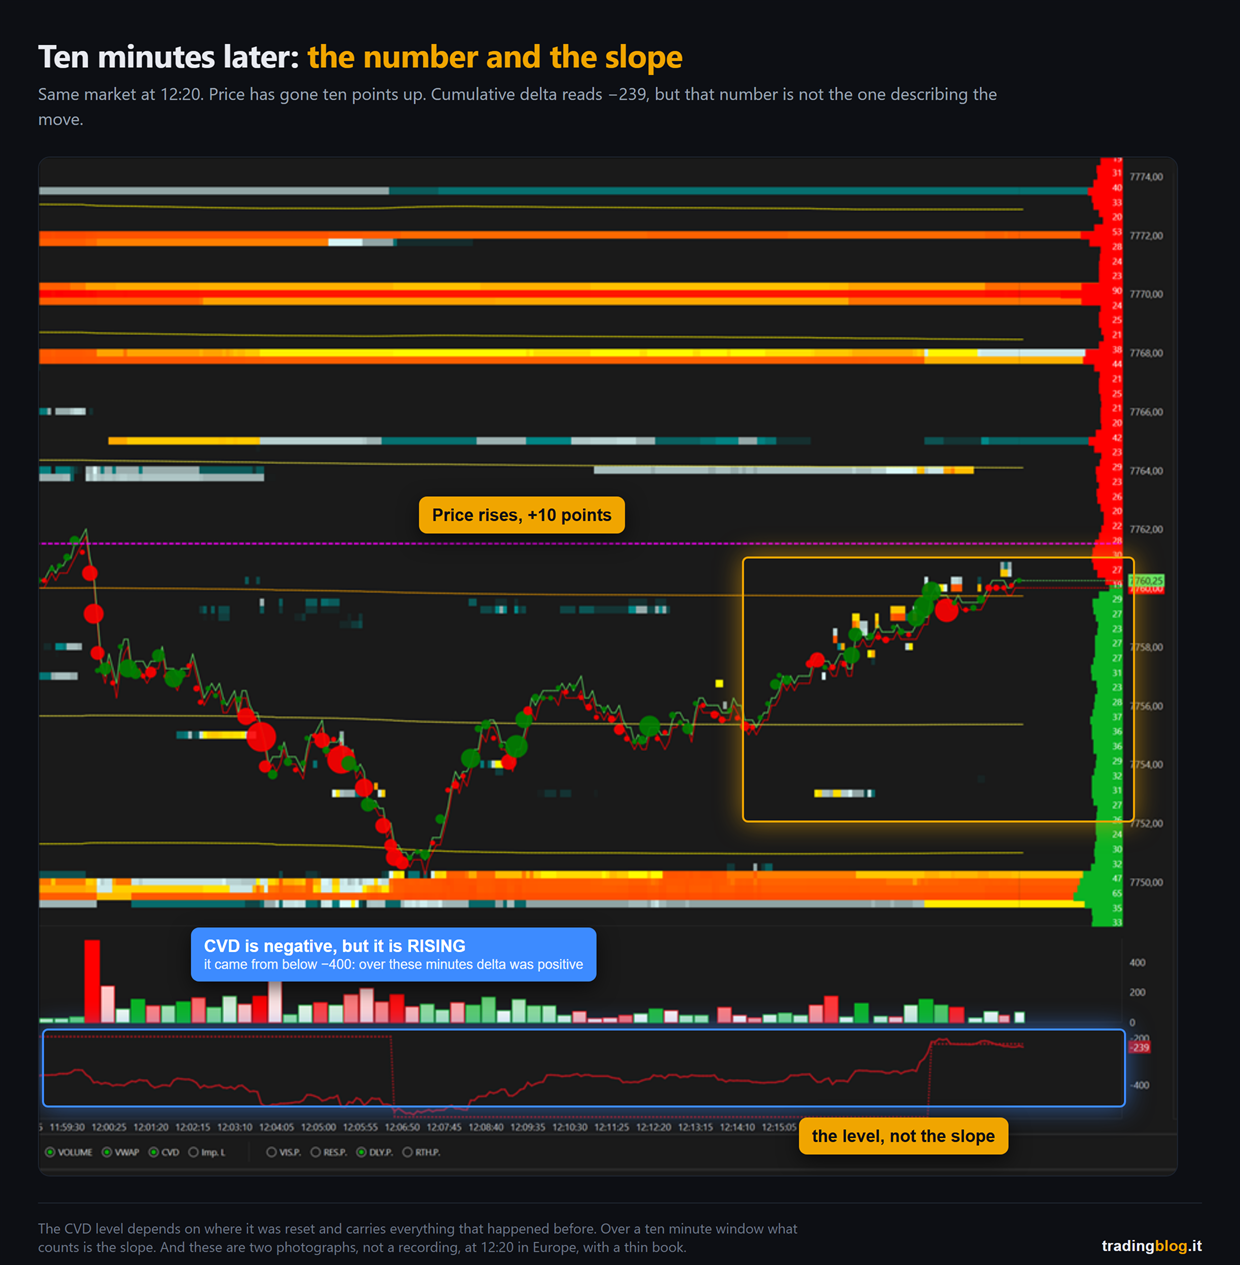
Real screenshot on ES at 12:20: price has risen ten points to 7,760.25 while in the bottom panel the cumulative delta line stays negative at -239
The same screen ten minutes later. Cumulative delta reads -239, but its slope is rising: it came from below -400.

Look at the figure, and look at the slope instead of the number.

Between 12:04 and 12:07 CVD had sunk below the -400 mark. From there it climbs without stopping, and across the window of the rise it goes from roughly -380 to -239.

Which means that over those ten minutes delta was positive by a hundred and something contracts. Somebody was buying and paying the spread, very much so.

That -239 was not describing the rise. It was describing the selling from twenty minutes earlier, still sitting inside it, because CVD is cumulative and carries everything since the last reset.

The level tells you where you are coming from. The slope tells you what is happening now.

And if you go back to the table from earlier, this case is not even a divergence: CVD rising, price rising, first row, normal, nothing to read. Effort and result added up.

It took me months to stop looking at the number and start looking at the tilt. If this piece saves you those months, it has done its job.

Two notes on this example, because I would be annoyed if nobody gave them to me.

These are two photographs, not a recording. They say the transition happened, not whether that ceiling was eaten or pulled.

And it was 12:20 in Europe, meaning US pre-market on the ES: thin book, few participants. Pulling size when there are few people around costs little, and the same read at 15:30 carries far more weight. Do not take the midday ruler and use it at the Wall Street open.

And the clean case of the third reason, the one where there really is nobody on the other side, I do not have in a single screenshot yet. When I capture it I will publish it. Better a hole I admit to than an example that proves something else.

The three traps, and all of them need saying

One. CVD depends on how it is calculated. Every platform decides in its own way how to classify fills, and the results are not identical. There is no “true” CVD and there is no best setting. What matters is knowing how your tool calculates it, and using one only. Comparing the CVD of two different platforms is like comparing two watches set by two different people.

Two. It is cumulative, so it depends on where it starts. A CVD starting at midnight and one starting at the cash open tell two different stories about the exact same afternoon. The absolute level means nothing: only the shape inside the window you chose matters. Pick one and keep it.

Three. On rollover days CVD is garbage. Volume splits across two contracts and the series stops making sense. It applies to volume, it applies to open interest, it applies here. Mark the quarterly rollover dates on your calendar and do not play doctor on those days.

And a note that concerns a lot of you: CVD is read on the future, where the volume is real and centralised. It is the structure I work with and I have always declared it: analysis on the future, execution wherever you trade. A CVD calculated on an instrument without centralised volume is not measuring what it thinks it is measuring.

“A sold rally”

Two words about this expression, which you will hear everywhere.

In the head of whoever says it, it means: price is going up but CVD is going down.

The fact itself can perfectly well be true. It is the conclusion they pull out of it, namely “so now it goes down”, that does not hold.

First, because it can be the third case: there is no aggressive selling, so CVD does not go up, but price goes up anyway because there is no supply.

Second, and more importantly: it is not an entry, because it does not tell you where to enter. An entry is a price. A divergence is not a price, it is a shape.

The line to take home

A divergence is not a signal. It is a question.

The question is “who is absorbing?”, and the answer is not on the CVD. It is on the book.

I look at the book in the DeepDOM.

Two lines of transparency, which feel owed: that above is an affiliate link. If you use it and subscribe I earn a commission, and you don’t pay a cent more.

If you look at the book and there is nobody there, the answer is “nobody”, and then there was nothing to see in the first place.

Used well, CVD is a confirmation that adds to a level you had already marked this morning. It is never the reason that level exists.

Which is also why, in my order of switching instruments on, CVD is the last one. Not the first.

What you do from tomorrow morning

Small homework and for a week you do not trade it, as always.

Mark down ten divergences. They do not need to be pretty, take the first ten you see.

For each one, at that same moment, look at the book and write one single word: was there real size on that level, yes or no.

Then wait and write down how it ended.

At the end separate the two groups and count them.

What almost always comes out is that divergences with size on the book and the ones without behave differently, and that the ones without are the majority.

After that homework you will never look at CVD on its own again, which is exactly the point. If you don’t have a place to keep the notes, the TradingBlog Diary is free and exists for this.

CVD measures who is in a hurry. The book shows who is standing still. Looking at only one of them is like listening to half an argument.

— tradingblog.itPosta su X

Let me close with the thing that saved me the most money in this whole story.

It was not learning to read CVD.

It was stopping asking it for what it cannot know.

It tells you who was running. Who was standing still on the other side, and whether they were big, that has to be told to you by a different instrument.

When two different instruments tell you the same thing, that thing stops being your opinion.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.