Posts

The trader of the future with the amber visor rests his hand on a large glowing metal dial, connected by rays of light to a volume profile in which the central band of bars glows amber while the others stay dark

The value area is not 70%. It is a knob.

Hi trader,

for years I looked at the lower edge of the value area as if it were carved in stone.

Then one day I opened the exact same session on two different platforms, and the two VALs were not at the same price.

Same future, same session, same trades. Two numbers.

Nothing was broken. The two platforms simply were not doing the same calculation, and neither of them had ever asked me about it.

That is where a question started that I suggest you ask yourself too, because it is one of those that move things: how many of the levels on my chart are a measurement of the market, and how many are somebody else’s default?

Ok, vamos.

What we are actually looking at

The volume profile is a histogram turned on its side.

For every price level it tells you one thing only: how much was traded there.

From that histogram the platform pulls out three numbers and draws them on your chart:

  • the VPOC, the price where the most volume of all went through
  • the VAH and the VAL, the two edges of the value area

The first one is a measurement.

The other two are a choice.

And the whole difference between a measurement and a choice is what this piece is about.

If the vocabulary is missing (TPO, initial balance, how the Market Profile bell is born), start from the piece where we took poor highs and poor lows apart, and then come back here. That one is the language, this one is the handle.

Where the 70% comes from

The Market Profile was born at the CBOT in Chicago in the 1980s, out of Peter Steidlmayer’s idea of representing the day as a distribution: the prices where the market spends most time sit in the middle, the rejected ones sit in the tails.

If that distribution really were a gaussian, one standard deviation around the mean would contain 68.27% of the cases.

Round it up, and there is your 70%.

So the number almost everybody treats as a property of the market is this: a rounded statistic borrowed from a theoretical curve.

And the theoretical curve is exactly the problem.

The profile of a real session is almost always anything but a gaussian. It has two humps, it has fat tails on one side only, it has holes in the middle. Trend days are stretched out distributions that look nothing like anything symmetrical.

So we are applying a convention born on an ideal curve to a shape that is never that curve.

It is not a reason to throw the value area away, which remains the most honest tool we have for saying “in here the market accepted, out there it rejected”.

It is a reason to know that the market did not decide that 70. A tradition did.

How the area is really built, which is the part nobody looks at

This is where the most common misunderstanding of all lives.

The value area is not the central 70% of the day’s range.

It is the result of an algorithm that starts from one precise place and widens:

  1. you start at the VPOC
  2. you look at the two levels above and the two levels below
  3. you take the pair that brings more volume, and you add it whole
  4. you repeat until the volume inside reaches the chosen percentage

Two practical consequences come out of this mechanism, and they are worth more than the definition.

The area is not symmetrical, and it is not supposed to be. It grows on the side where there was more activity. If the VAL is miles away from the VPOC while the VAH is glued right on top of it, that is not a software defect: it is the shape of the day telling you which side something happened on.

The edges move in jumps. They get added in pairs, and one fat level just outside the edge can come in all at once. One extra percentage point on the knob sometimes moves nothing, and sometimes moves your VAL by six ticks. It depends entirely on what is sitting out there.

And here is the detail that explains the story I opened with: not every platform widens in pairs. Some add one level at a time, picking the heavier side each step. They are two different algorithms that start from the exact same profile and end up on slightly different edges.

Neither one is right and neither is wrong. The point is that one of the two is on your chart and you probably do not know which.
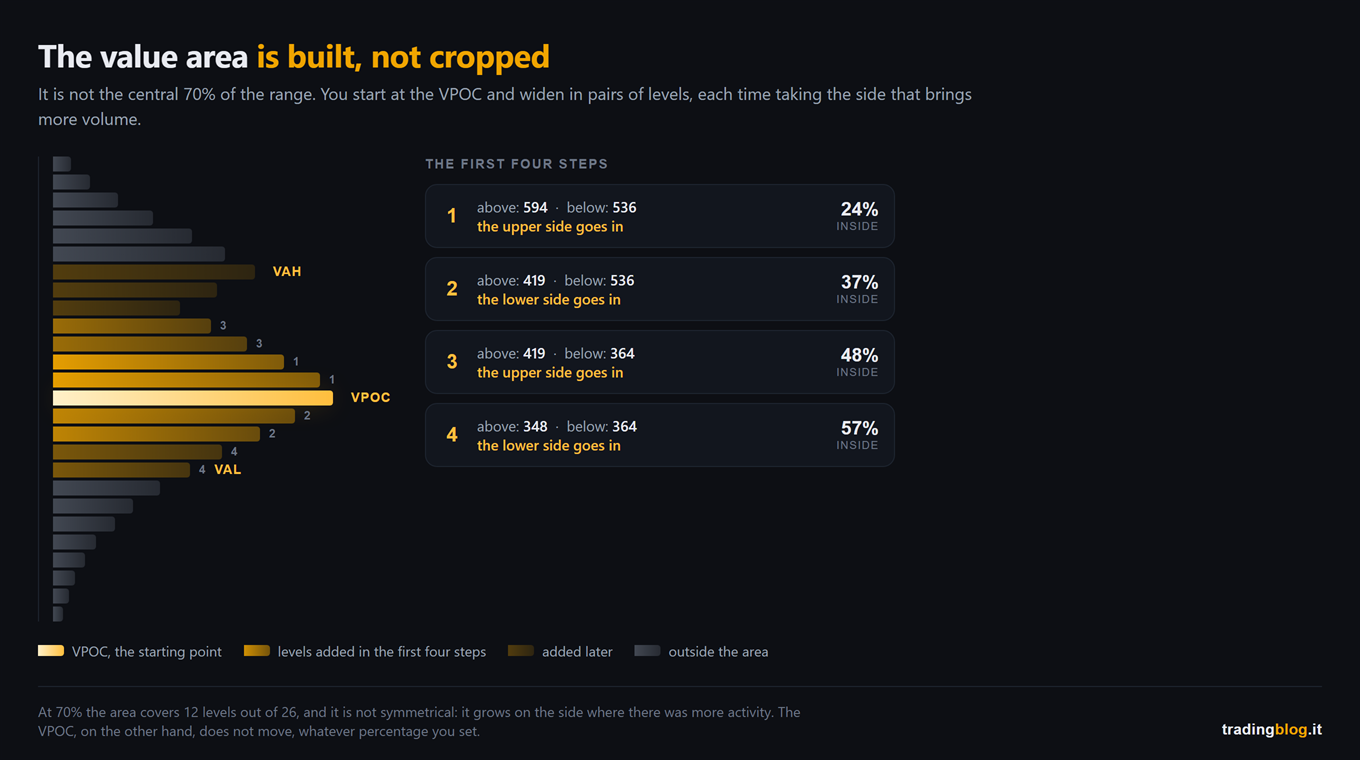
A session volume profile with the value area built step by step starting from the VPOC: the levels added in the first four steps are in bright amber, those added later in dim amber and those outside the area in grey, with the comparison between the volume of the two levels above and the two levels below at each step shown alongside
How the value area is really built. You start at the VPOC and widen in pairs of levels, each time choosing the side that brings more volume, until you reach the percentage you set.

Turn the knob yourself

This is the same thing, but with your hands on it.

Below is a session profile. The slider decides how much volume you want inside the area.

Take it to 50, then take it to 90, and watch where the two edges end up.

Then look at the VPOC.

It has not moved.

The one thing that does not depend on you

The VPOC is the only level on the profile that does not depend on the percentage you set.

That is not an opinion, it is a maximum. The level where the most volume went through is that one, no matter how you turned the knob.

Which is why, if I have to keep one single level off the profile, I keep that one.

That said, I do not want to sell you the VPOC as an oracle, because there is more than one knob.

The VPOC still depends on which session you are profiling. If you profile the US session only or the full 24 hours, the centre of gravity can land in two different places, and not by a little. That is a setting of yours too, it just lives in another menu.

And it depends on what you are counting. The classic Market Profile counts time, that is, how many half hours touched that price. The Volume Profile counts contracts. In the exact same session the time POC and the volume POC can sit at different levels, and anybody who looks at “the POC” without knowing which of the two they are looking at will sooner or later argue with a friend who has the other one.

This is not nitpicking. It is that when you open a chart shared by another trader, those three levels on it are three of their choices too.

What actually changes in your trading

That was the theory. Now the part that touches your account.

If the edge of the area is the result of a percentage, then the right question is not “did price touch the VAL”.

The right question is: what is behind this edge?

Because there are two very different edges that look identical on a chart.

There is the backed edge: the percentage ran out right there, but just below it the profile carries on nice and fat. If price breaks through it does not find emptiness, it finds more people who traded. It is a break that is born with no room.

And there is the edge facing the hole: below the VAL the profile thins out immediately, a few skinny rows and then nothing. There a break has an open road, because price travels fast through the areas where almost nothing was traded.

Same level, same label, two opposite situations.
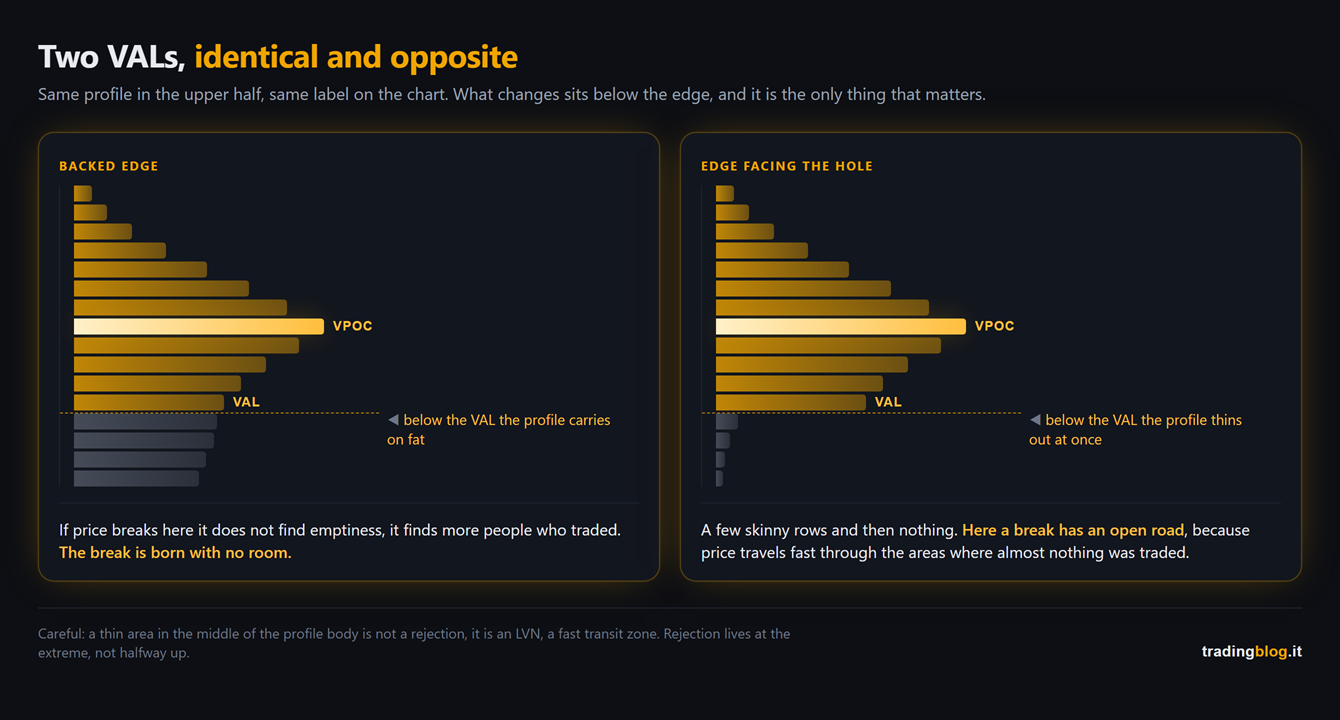
Two volume profiles side by side with an identical upper half and the same VAL label on the edge: in the first one the volume stays dense below the edge, in the second the profile thins out immediately and leaves an almost empty area where price can run
Two VALs with the same label and the opposite meaning. On the left the backed edge, with dense volume just below. On the right the edge facing a thin area, where price has an open road.

One clarification is needed here, because it is a mistake I have already seen made: that thin area, if you find it in the middle of the profile body rather than at the extreme, is not a rejection. It is an LVN, a fast transit zone. We covered it when we took poor highs and poor lows apart, and the difference between a notch at the extreme and a notch halfway up the body completely changes what you should expect.

And this is where everything we did over the summer hooks back up.

The profile tells you where to look. The footprint and the delta tell you what is happening while price gets there.

At the edge the question is always the same one we asked ourselves talking about bid/ask candles and about CVD: who is in a hurry, and who is sitting still and waiting.

A level on its own has never saved anybody. A level plus the context of who is attacking it, that one has.

The acid test on your own rules

There is a test you can run tonight, and it is brutal.

Take one of your rules that uses the edge of the value area. Any of them: “I do not buy above the VAH”, “if it opens outside the area the day is directional”, whatever it is.

Now run it again at 60% and run it again at 80%.

If the outcome changes, that is not a rule about the market. It is a rule about your settings.

It does not mean throwing it away. It means you have found out that it is fragile, and that either your real level is somewhere else, or you need one more condition to keep it standing.

Better to find that out on a chart tonight than with money on the line on a Wednesday afternoon.

What you do from tomorrow morning

Three things, and the first one takes two minutes.

Open your platform and write down three pieces of information in black and white: what percentage it is using, whether it counts volume or time, and which session it is profiling. If you cannot answer one of the three, that level on your chart is not yours. It belongs to whoever wrote the default.

Put two profiles on the same chart, one at 60 and one at 80, and keep them for a week. Not to trade off them. To see how much the edges swing on your instrument and your hours, which is not how they swing on mine.

The VPOC, on the other hand, treat it for what it is, the centre of gravity of that day’s auction, and mark it. The interesting part is not where it sits today, it is what price does when it comes back to it tomorrow or next week.

And if you mark them in your diary instead of in your memory, in a month you have a statistic of your own instead of an impression. The difference between those two things is the whole craft.

The VPOC is a measurement. The value area is a setting. On a chart they look like the same thing.

tradingblog.itPosta su X

Let me close with the thing that changed my head on this subject.

It was not finding out that the 70% is a convention. That is bar trivia.

It was realising that I was making decisions with real money leaning on a number I had not chosen, had never checked, and could have changed with two clicks.

Since then, the first day I open a new platform, I look at the indicator settings first and the market second.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.

Monumental wall of stacked glowing amber blocks emerging from the dark, its top sliced perfectly flat, with a faint scaffolding of light hovering above the cut like a job left half done

Poor high and poor low: the extreme that never finished the job

Hi trader,

I was shorting it with the face of someone who has understood everything.

Yesterday’s high, today’s high, same price to the tick. A textbook double top, the kind that makes people write “very strong resistance” with three exclamation marks in the Telegram groups.

Order in, stop above, off we go.

Price went through it like a knife through butter. Not even a pause out of politeness.

It took me years to understand that that high was not a resistance.

It was a job left half done.

First the name, which is already half the explanation

In the communities they call it a bad high and a bad low.

In the serious books the name is different, poor high and poor low, and it comes from Market Profile, the method Peter Steidlmayer developed at the CBOT in the Eighties to read the market as an auction instead of as a chart.

I use both names because you will hear both. But keep the second one in mind, because that is the one telling you the right thing.

Poor means poor, shabby.

Not “strong”, not “resistance”. Poor.

It is a badly made extreme, and the market usually comes back to make it properly.

Ok, vamos, let’s take it in order.

How an auction ends when it ends well

The market is an auction. It goes up until it finds someone willing to sell in size, it goes down until it finds someone willing to buy in size.

When an upside auction really ends, it does not end from tiredness.

And above all it does not end because price went “too high”. Get that idea out of your head, it does not exist: there is no such thing as a price that is too high in absolute terms, and whoever sells because “it has gone up a lot by now” finds that out the hard way, usually another two hundred points later.

It ends because price reaches the place where somebody actually wants to sell in size. There it finds serious sellers, and from there it gets rejected fast.

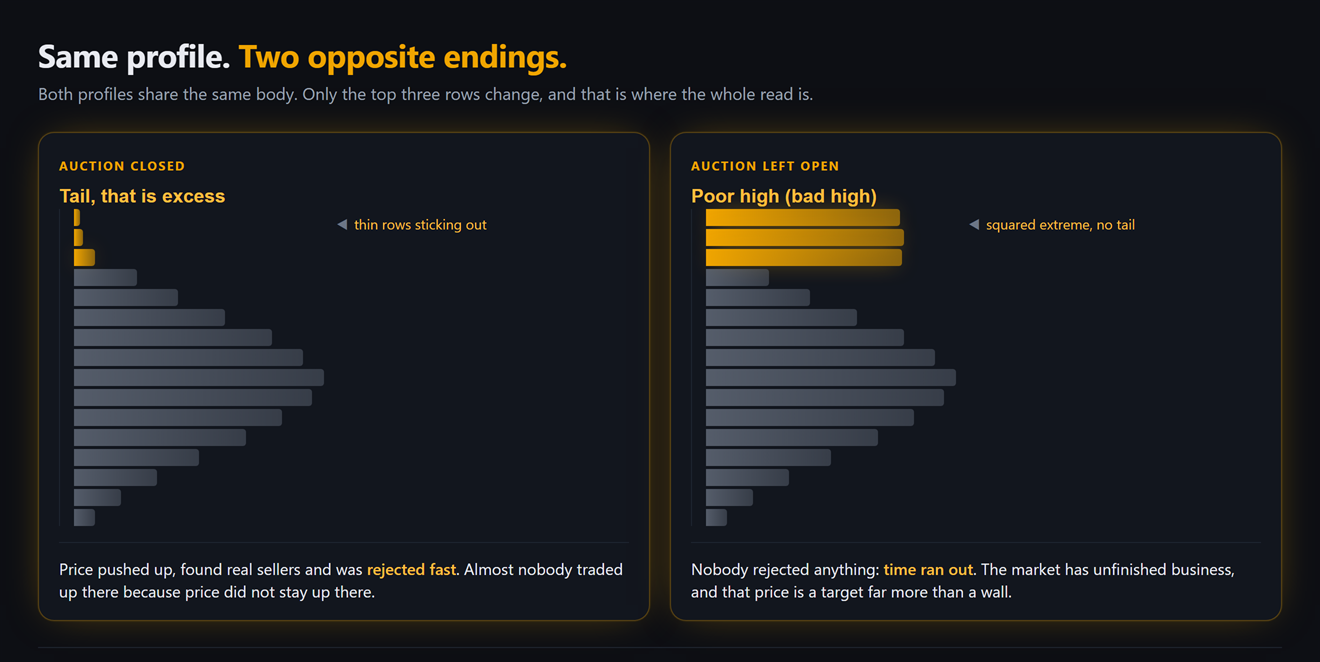
That speed leaves a mark, and it has a name: excess.

On the profile you see it as a spike sticking out: two or three very thin rows with very low volume, stuck on top of the fat body of the profile. In classic Market Profile those are the single prints of the tail, meaning prices that in the whole session only one thirty minute period traded.

The meaning is simple: almost nobody traded up there because price did not stay up there long enough to allow it.

It was pushed up, rejected, and brought back down.

That is a closed auction. The market asked the question, got the answer, turned the page.

Two session profiles side by side sharing the same body: on the left the upper extreme ends with three thin rows sticking out, the excess of a closed auction, on the right it ends squared off with three full rows aligned at the same price, a poor high
Two session profiles side by side. On the left the upper extreme ends with a thin tail sticking out, the excess, which is an auction that closed properly. On the right it ends squared off, with two full rows aligned at the same price, which is a poor high.

And how an auction ends when it ends badly

Now look at the profile on the right of the picture.

No spike. No tail.

The extreme is squared off, cut clean, with two or more full rows aligned at the same price. In Market Profile terms you would say two or more TPOs ending exactly there.

That high was not rejected by anybody.

Time simply ran out.

Bell rang, shop closed, and price was still up there trading happily at the high of the day. Nobody told it no. Its session just expired.

Which is why in English it is also called unfinished business.

And unfinished business, in markets as in life, sooner or later comes knocking.

The spike that gets you, because not all spikes are the same

This is where ninety per cent of the people who have just discovered volume profile fall over, and I fell over here too.

You see a thin band, you say “excess”, you lean a trade on it.

Three cases where it is not.

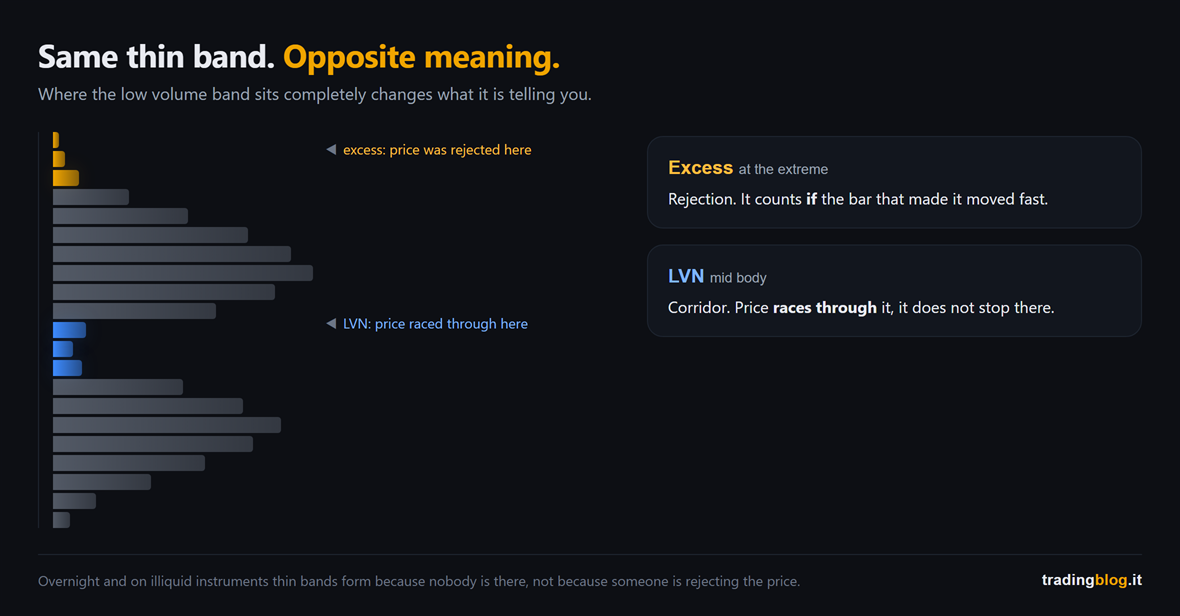
One. A spike in the middle of the profile is not an excess.

If the thin rows are in the middle, and not at the extreme, they have another name and another meaning: it is called an LVN, a low volume node.

It is not a place where somebody rejected the price. It is a place where price raced through without anyone wanting to negotiate.

It is a corridor, not a wall. And the operational consequence is the opposite: on an LVN price tends to slide fast, not to stop.

A session profile with two thin bands highlighted: the one at the top, in amber, is an excess and marks rejection, the one mid body, in blue, is a low volume node and marks a fast transit area
A single session profile with two thin zones highlighted. The one at the upper extreme is excess, meaning rejection. The one mid body is an LVN, meaning a fast transit area. Same shape on the chart, opposite meaning.

Two. An excess without speed is not an excess.

The spike counts if the bar that created it moved fast. Rejection means violence, it means price came back in a hurry.

If those thin rows formed over twenty minutes of price floating around, you did not see a rejection.

You saw stagnation with few trades, which is another thing entirely and gives you no rights.

Three. At night, spikes are worth nothing.

On futures the overnight session, and illiquid instruments in general, produce thin bands by the bucketload.

Not because somebody rejected those prices, but because nobody was there.

It is a skinny profile because the shop was empty, not because the goods were unappealing. Whoever reads those bands as rejection levels is reading the closing time and mistaking it for information.

And now the part that counts: what you do with it

Here I have to give you the uncomfortable news, the one that will probably annoy you about this piece.

A poor high is not a level to trade against.

The reasoning is straightforward, follow it.

The auction up there did not close. There was no rejection. Nobody defended that price.

So that price, far more than a wall, is a target.

A place where the market has a job to finish, where above it there are stops leaning from everyone who believed the double top, and where to get there it does not have to break any defence because the defence never existed.

That is exactly my short from the beginning: I had stood in front of a target thinking I was behind a wall.

And the operational translation is this, in two lines.

On a poor high you do not short aggressively. If you really do have a bearish idea, you do not play it there.

On a poor high, if anything, you bring a target. If you are long and above you there is a squared off high, you have one more reason not to close too early.

And above all: it is context, it is not a signal.

Nobody enters the market because they saw a squared off profile. It tells you what kind of ground you are walking on, it does not tell you to click.

The trigger stays the one you already have: how price reacts when it gets there. It gets there, slows down and reacts, or it goes straight through without even slowing down. That is the answer, and it always comes after, never before.

If you read the two order flow pieces from the last few weeks, you already have the microscope for that moment: in the bid/ask candles you see who is trading at the level, and with absorption and exhaustion you work out whether anyone is actually defending it.

The profile tells you how the auction ended at that price. Order flow tells you who is there now.

They are two different questions about the same spot on the chart, and that is why they go well together.

The percentage I am not going to give you

At this point of the conversation, live, they always ask me the same question.

“Ok Tiziano, but how often does a poor high get retested?”

And here I am going to tell you something that is not what you want to hear.

I don’t know.

I mean: there are numbers floating around, I have read them too, and I promise you that whoever fires them at you is not telling you on which instrument, in which years, on which timeframe and with which definition of “retested” they measured them.

Because the truth is that it all changes. It changes between ES and DAX, it changes between a full session and a thin August one, it changes depending on whether you count the touch to the tick or the genuine break.

A statistic you don’t know how it was built is not a number, it is an elegant way of guessing.

So the serious answer is: measure it on your market and in your hours.

You need very little. Every time you find a squared off extreme at the end of the day, you write it down. Then you write down whether price came back to it in the following days, and whether it took it out or not.

After thirty observations you have a percentage of your own, on your own instrument, and it is worth a thousand times the one from some guy on the internet. And above all you know how you counted it.

If you don’t have a place to keep these notes, use the TradingBlog Diary: it is free, it was built exactly to record observations and not just trades, and it saves you from the fate of every statistic done from memory, which is to confirm precisely what you already believed.

What you do from tomorrow morning

Small homework, as always. And for a week you do not trade it.

Turn the profile on for the session of the market you follow, and every evening look at the two extremes, the high and the low.

Then write one single word for each: tail, if the spike sticks out and it was born from a fast move, or squared, if it is cut clean.

That is all. No orders.

After two weeks open your notes and look at what happened the next day to the “squared” ones and what happened to the “tail” ones.

You need nothing else to build a view that is yours, and to stop having to take my word for it.

A high that nobody defended is not a resistance. It is a job left half done, and the market always comes back to finish its jobs.

tradingblog.itPosta su X

I want to close on something that goes well beyond the profile.

For years I looked at charts hunting for walls. Levels that hold, prices that reject, textbook resistances.

The day I started asking myself “this extreme, how was it formed?” instead, half of my levels disappeared from the map.

And it was the best thing that could have happened to my account, because those levels were not holding before either.

I just didn’t know it.

If this was useful, send it to that friend of yours who shorts every double top because “it’s a double top”. You’d be doing them a favour, and you might save their day.

Suerte Amigo!

Tiziano Brunno

Tradingblog

Want to put your market reading to the test?

Compete and challenge other traders inside an Arena in a demo environment, with no real capital at risk. Discover the Performance Arena Events by The Thunder Trader.

Discover The Thunder Trader →


Disclaimer: purely informational and educational content. It does not constitute financial advice or an invitation to trade. Trading involves the risk of capital loss.